Lending keeps growing
NBFC credit grew 14.4% year on year in June 2026 (retail +20.3%). Fintech lenders hire credit-risk analysts with SQL and Python; bureaus (CIBIL, CRIF, Experian, Equifax) employ scorecard and analytics teams.
Risk-management salaries by role and seniority in India and six global hubs, the regulatory changes driving hiring, 90+ employers with careers-portal links, real job descriptions, fresher entry routes and a step-by-step roadmap for FRM candidates. Prepared by RBei Classes Research Desk · Mentored by Deepak Goyal, CFA & FRM. Data as of 15 October 2026.
100% free · No spam · Call +91 8583905853
Three RBI rulebooks take effect on 1 April 2027, a model-risk framework is on the way, and global banks keep moving risk work to India. For FRM candidates, the next three years look like the strongest hiring window in a decade.
How to read the salary numbers: Indian pay is annual compensation in ₹ lakh (₹ L). Most role-level figures come from Glassdoor India and PayScale (self-reported); seniority bands come from the Michael Page India salary guide (base pay). Treat every figure as a guide to the band, not an offer.
Risk teams grow when regulation tightens, lending expands and global banks centralise analysis. India has all three at once.
| Regulation | Status | Effective | What it requires | Skills in demand |
|---|---|---|---|---|
| Expected credit loss (ECL) | Final directions 27 Apr 2026 | 1 Apr 2027 | Internal PD/LGD/EAD models with macro overlays; board oversight; independent validation | Credit risk modelling, model validation, IFRS 9 |
| Basel III credit risk (standardised) | Final directions 27 Apr 2026 | 1 Apr 2027 | Revised risk weights and capital calculation | Credit risk, capital, regulatory reporting |
| Basel III market risk | Market Risk Directions 21 Sep 2026 | 1 Apr 2027 | Simplified standardised approach for market-risk capital | Market risk, treasury, reg. reporting |
| Model risk management | Draft guidance 24 Jun 2026 | TBD | Board-approved framework; independent validation incl. vendor & AI/ML; bias testing; kill switch | Model validation, AI model risk |
| Operational risk capital | Finalised 26 Jun 2023 | To be notified | Basel III new standardised approach | Operational risk, ERM |
| SEBI MF risk framework | In force since 1 Jan 2022 | In force | CRO at every AMC; monthly stress tests; liquidity-risk models | AMC risk teams |
NBFC credit grew 14.4% year on year in June 2026 (retail +20.3%). Fintech lenders hire credit-risk analysts with SQL and Python; bureaus (CIBIL, CRIF, Experian, Equifax) employ scorecard and analytics teams.
India had 2,117 GCCs with 2.36 million people in FY26. More than 190 serve banking and finance (540,000+ staff). Model validation for global banks increasingly sits in India; BFSI GCC office leasing hit a record 7.32 million sq ft in H1 2026 (+70%).
Control roles (CRO, CCO, CFO) made up 22.4% of NBFC and housing-finance leadership moves in 2025. Taggd lists risk managers, credit-risk and risk-modelling specialists among the hardest BFSI roles to fill, with a 42% AI and data skill gap in BFSI GCCs.
GARP's two-part global risk certification. Fees: enrolment $400; each part $600 early / $800 standard (total ~$1,600–2,000 plus GST). 2 years relevant experience required for certification. 100,000+ certified FRMs worldwide; 6,000+ in India (GARP 2021).
The FRM syllabus maps directly onto each track. Modelling tracks need Python, SAS and statistics; credit and operational tracks reward analysis and judgement.
Analyst → Associate → AVP → VP → Head of Market Risk
Credit Analyst → Manager → AVP → Head of Credit
Analyst → Senior → Lead → Head of Modelling
Analyst → AVP → VP → Head of Model Risk
Analyst → Senior Analyst → VP
Analyst → Manager → Head of ALM
Analyst → Manager → Head of ORM
Analyst → Manager → CRO
Analyst → Manager → Head of Reg. Reporting
Analyst → Specialist → Head
Modelling and quantitative roles pay the most early on; operational risk and generalist analyst roles start lowest. The jump comes at AVP, where base pay roughly doubles from analyst level.
| Role | Average | Range | Employer medians / note |
|---|---|---|---|
| Risk Analyst (generic) | ₹5.5 L | ₹4–10 L | Entry ₹3.9 L; 1–4 yrs ₹6.0 L (PayScale) |
| Market Risk Analyst | ₹13.05 L | ₹8–18 L base | Glassdoor (50), Aug 2026 |
| Market Risk Manager | ₹17.5 L base | ₹10–28.3 L | ICICI 19, Barclays 18, Deutsche Bank 9 |
| Credit Risk Analyst | ₹12.9 L | ₹9–17 L | JPMorganChase 19, Citi 16, HDFC Bank 13 |
| Credit Risk Manager | ₹11.2 L base | ₹8–15 L | StanChart 15, HSBC 14, Axis 14, HDFC 9 |
| Credit Risk Modeller | ₹12.5 L | — | J.P. Morgan 20, EXL 16, HSBC 10 |
| Model Validation Analyst | ₹17 L | ₹15–28 L (median 23) | UBS 21, ANZ 12 |
| Quant Analyst (risk) | ₹19 L | ₹10.5–25 L base | Goldman Sachs 30, Wells Fargo 25, JPMorgan 24 |
| Counterparty Credit Risk | ₹14 L | — | HSBC 14 |
| Treasury / Liquidity Risk | ₹10.4–12.1 L | ₹8.4–20 L | Goldman Sachs liquidity risk mgr 42 |
| Operational Risk Analyst | ₹5.66 L | ₹5–17 L | Citi 7, Wells Fargo 5 |
| Regulatory Reporting Analyst | ₹11.3 L | ₹7.1–13.9 L | UBS 11, KPMG 8 |
| Enterprise Risk Management | ₹21.5 L | ₹11.4–29.5 L base | Chola MS 32, EY 15 |
| Risk Consultant (Big 4) | ₹9 L | ₹6–10 L base | EY 10, KPMG 9, Deloitte 8, PwC 7 |
| AVP Risk | ₹27.25 L | ₹25–35 L base (Michael Page) | HSBC 36, IndusInd 24, Tata Capital 21 |
| VP Risk | ₹38 L | ₹35–55 L base (Michael Page) | NatWest 50, RBL 30 |
| Chief Risk Officer | ₹47 L (Glassdoor) | ₹10–99 L (AmbitionBox) | Large bank total cash ₹3.5–7 Cr+ |
Glassdoor sample sizes vary; some role pages have few submissions or older data. Use figures as directional only. Global bank GCCs and quant-heavy roles pay a clear premium over Indian banks and Big 4 at similar experience.
Risk is one of the few finance functions with structured graduate programmes at global banks in India. The rest of the market hires through Big 4, analytics firms and bank management-trainee schemes.
Barclays Risk Analyst Graduate (Noida); Deutsche Bank CRO India Grads; Wells Fargo Corporate Risk QAP & CRDP; Goldman Sachs New Analyst; Morgan Stanley, JPMorgan, UBS, Standard Chartered intern/risk programmes.
Deloitte Risk Advisory; EY GDS FSRM; KPMG IA & Risk Advisory; PwC Risk Consulting — campus hiring for stats/finance/engineering degrees.
EXL, Genpact, WNS, Crisil, Moody's, S&P, MSCI; fresher-friendly GCC roles at Goldman Sachs Regulatory Reporting, State Street, BNY.
FRM Part I cleared on CV/LinkedIn; Python & SQL project (VaR, PD scorecard, backtest); Excel modelling; ECL vs incurred-loss literacy; Basel pillars; clear writing.
Smart sequencing: Clear Part I in your final year or first job → join a GCC risk team, Big 4 risk advisory or bank credit department → clear Part II within 12–18 months → certify after two years' relevant experience. Model validation and ECL projects are the fastest-growing areas. For market risk / validation / quant: FRM + strong Python. For credit / ERM: FRM + CFA Level I adds valuation depth.
Risk is one of the most transferable finance skills because Basel, IFRS 9 and model-risk standards are global. Practical routes: study-then-work, internal transfer and Gulf hiring.
A $100,000 fee applies to new H-1B petitions for workers outside the US (confirm current status on uscis.gov). F-1 to H-1B change of status inside the US is exempt. Lottery is wage-weighted. Practical route: US master's, then H-1B from inside the US.
Skilled Worker general threshold £41,700 (new entrants £33,400). Graduate visa falls to 18 months from 1 Jan 2027.
Singapore EP minimum for financial services S$6,200/month (S$6,600 from Jan 2027) + COMPASS. UAE: no personal income tax; Golden Visa for skilled pros earning AED 30,000+/month.
Nine of GARP's top FRM employers run teams in India. Two to four years in a GCC risk team, the FRM, and strong reviews often open moves to Singapore, London, Hong Kong or New York without an open visa lottery.
Immigration rules change often. Confirm on official government sites. This page is for educational guidance only — not immigration advice.
A practical sequence built from what risk employers in the report actually test for.
This FRM Careers 2026 research is mentored by Deepak Goyal, CFA & FRM Charterholder, who has been teaching FRM and CFA for the last 10 years. RBei Classes students clear exams at a 93% success rate, with named FRM results published on the student-results hub.
Every FRM session at RBei Classes is taught by him personally — not junior or outsourced faculty — so candidates get risk concepts, exam strategy and career guidance from a dual charterholder who also leads this career research desk.
Download the full report, then talk to RBei Classes about FRM Part 1 & 2 coaching with Deepak Goyal, CFA & FRM Charterholder.
Disclaimer: Prepared by RBei Classes Research Desk for student guidance. Not investment or immigration advice. Salary figures are indicative bands from Glassdoor, PayScale, Michael Page and related sources; they are not offers. FRM® is a trademark of GARP. RBei Classes is an independent coaching provider and is not affiliated with or endorsed by GARP. Full methodology and sources are in the downloadable report. Data as of 15 October 2026.
RBei Classes, an FRM & CFA coaching institute founded in 2018 by Deepak Goyal (CFA & FRM charterholder), has trained thousands of students who share their results publicly on LinkedIn. The 13 posts below are a sample of RBei Classes students announcing verified CFA and FRM passes — public, name-attributed proof of outcomes.
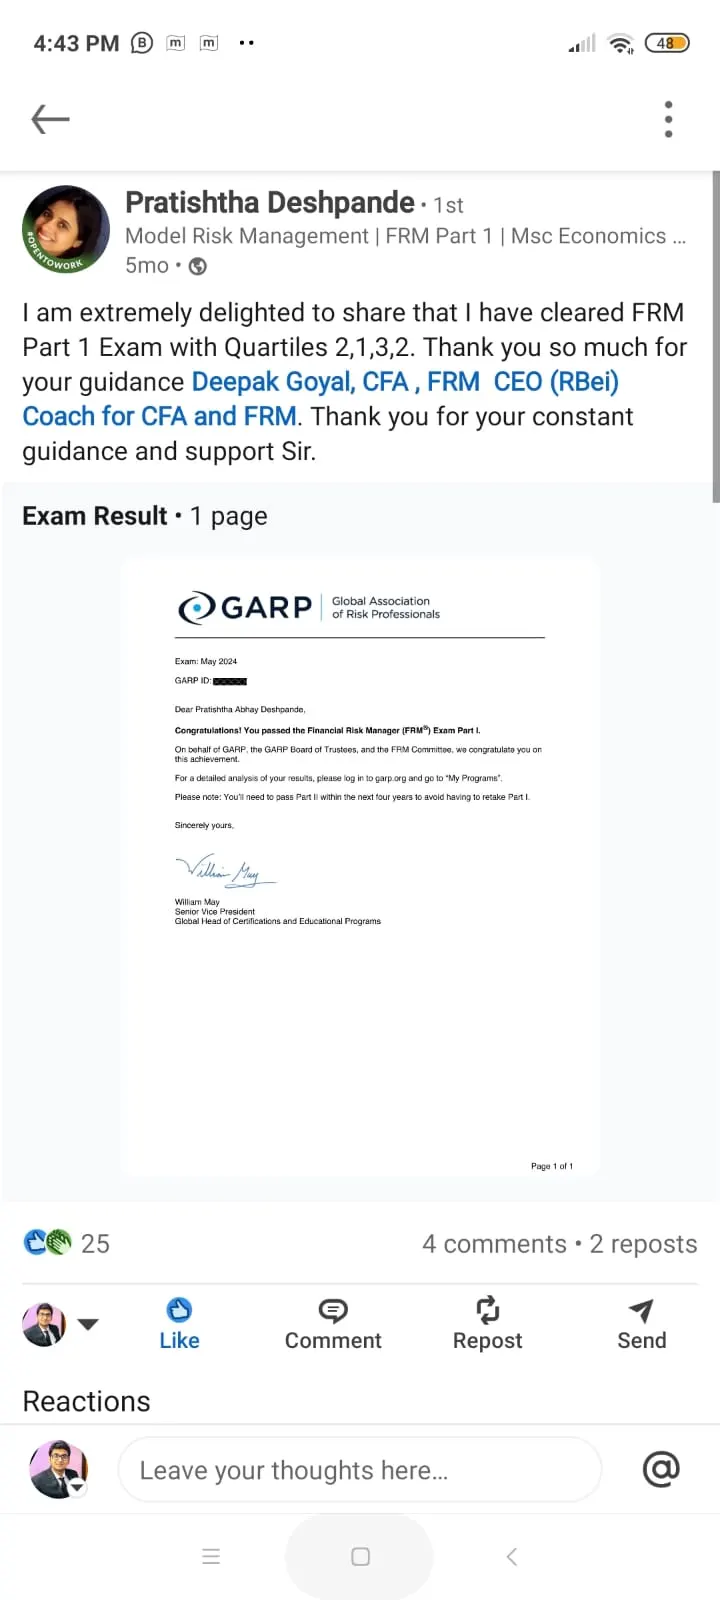
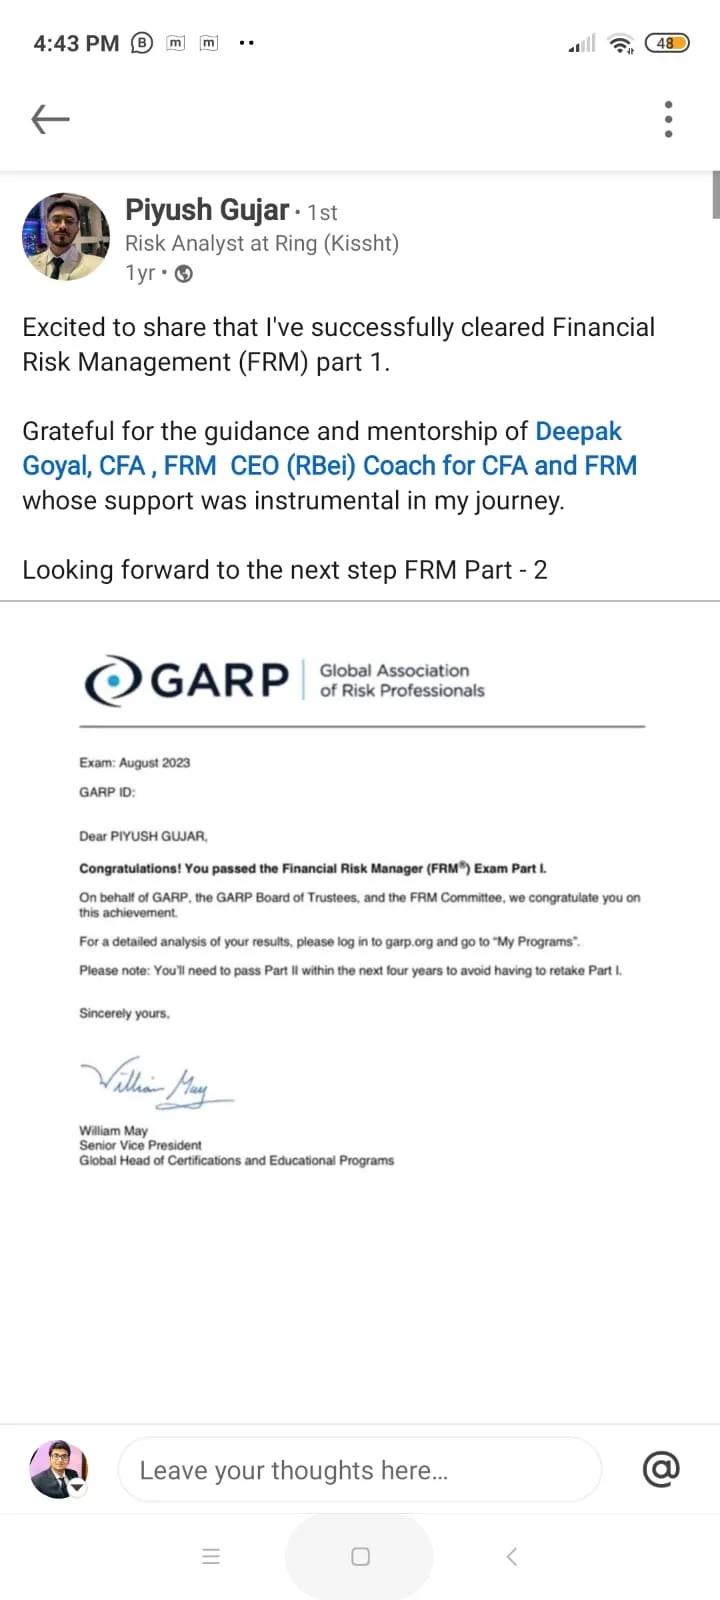
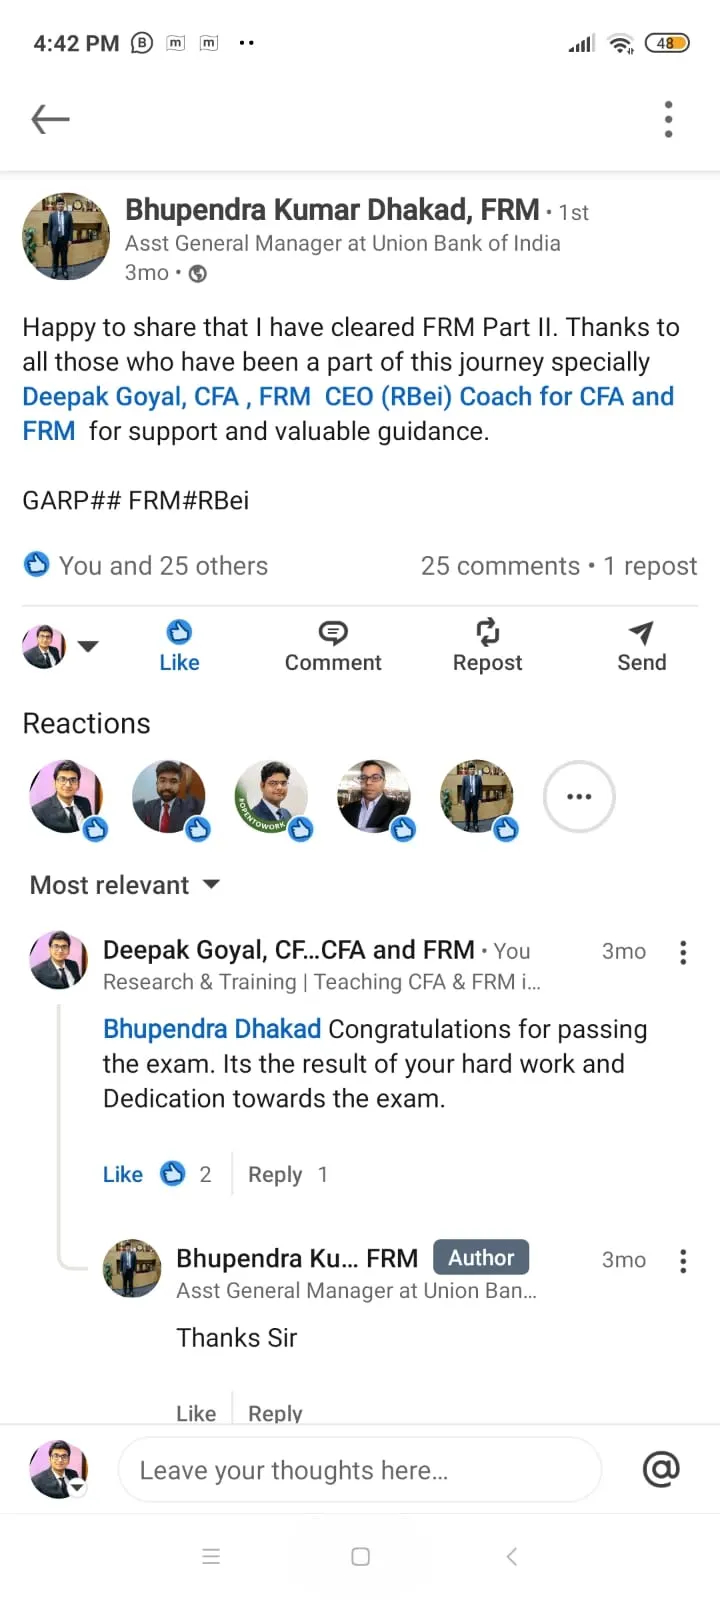
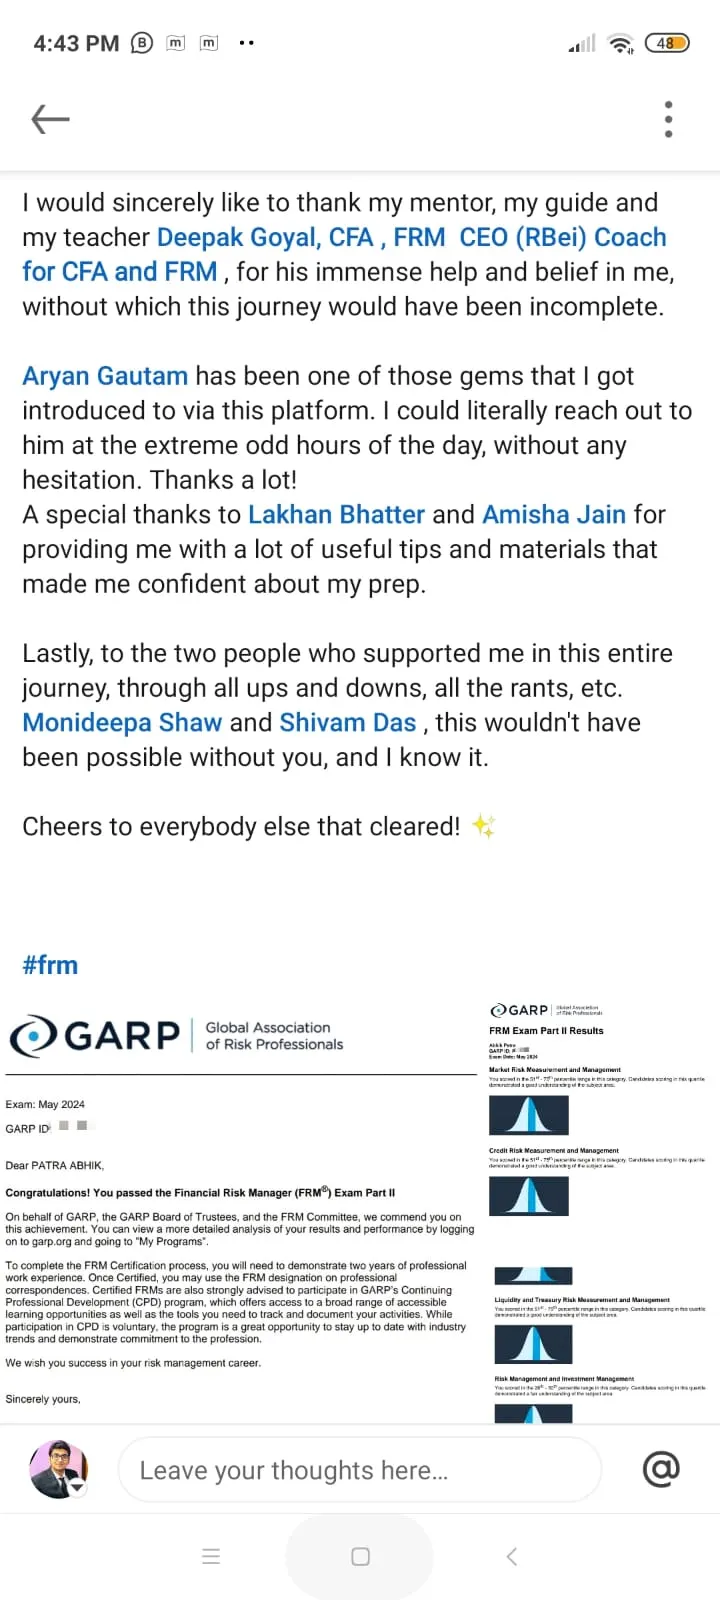
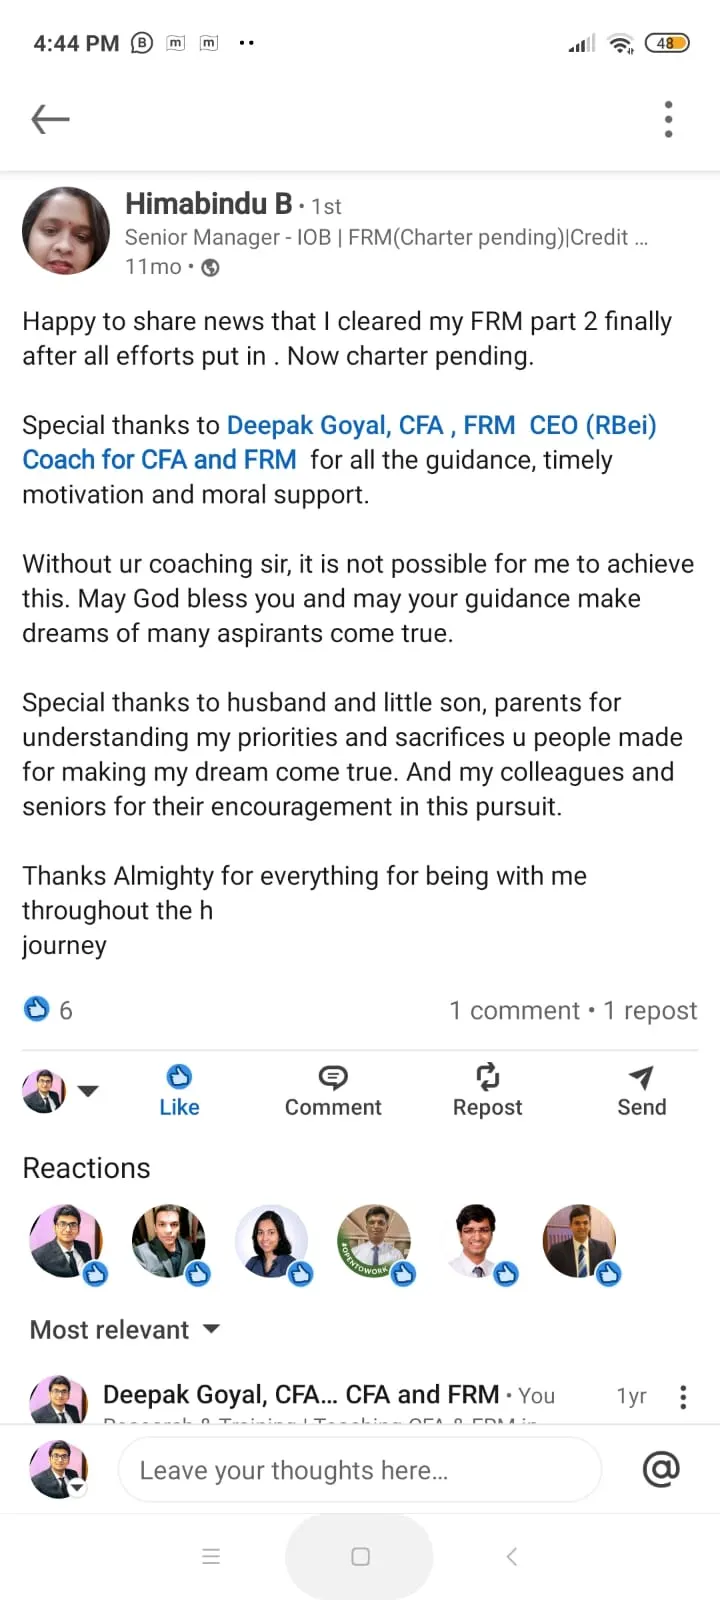
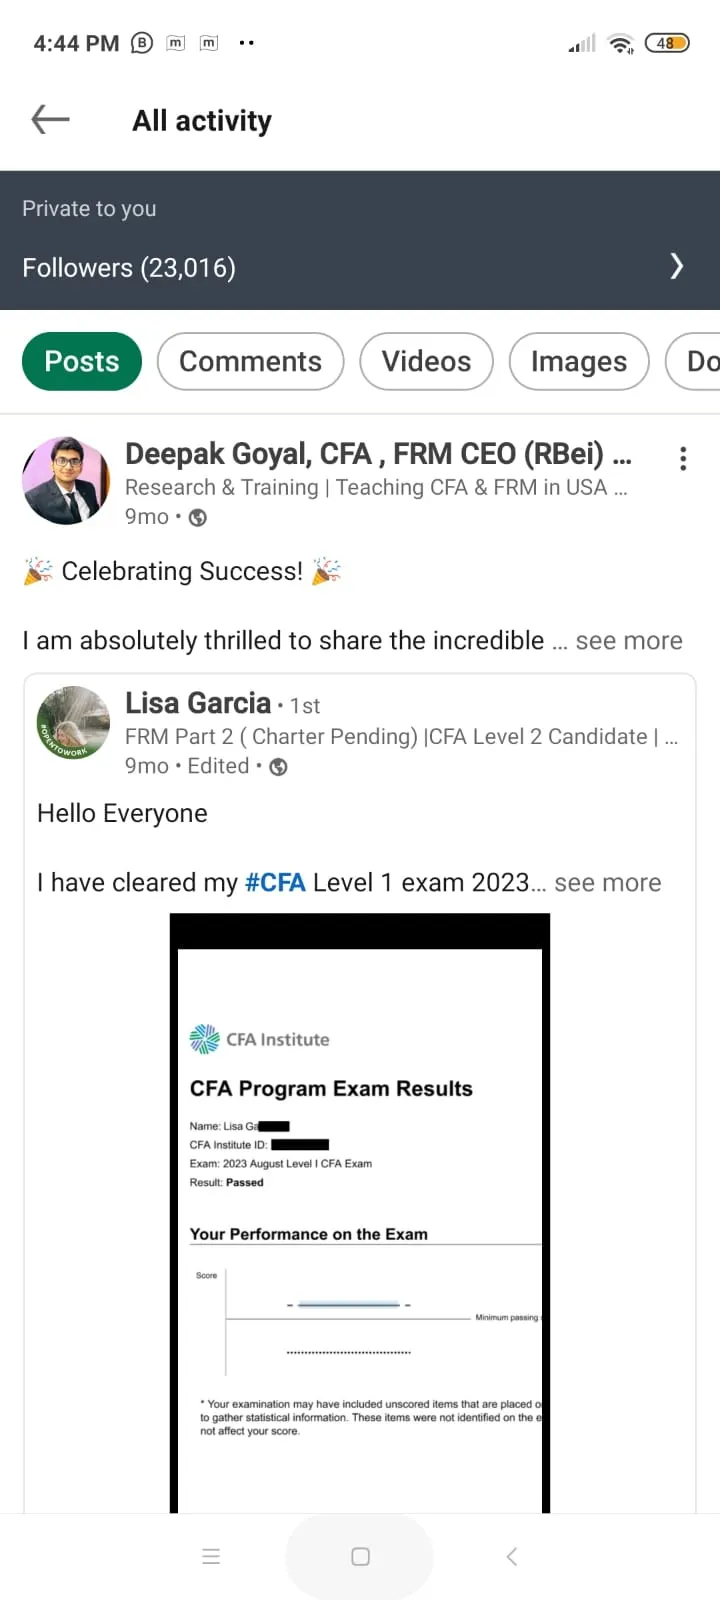
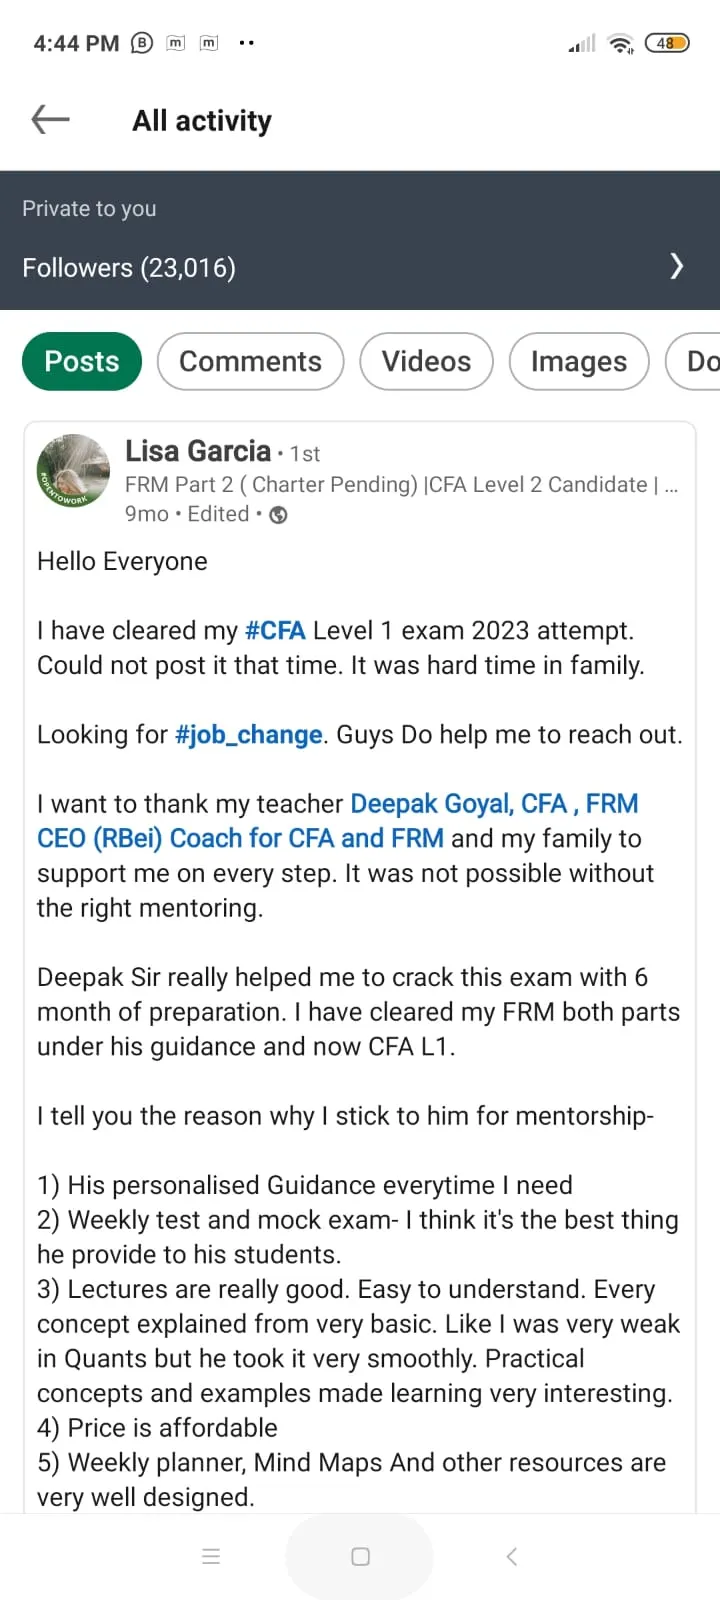
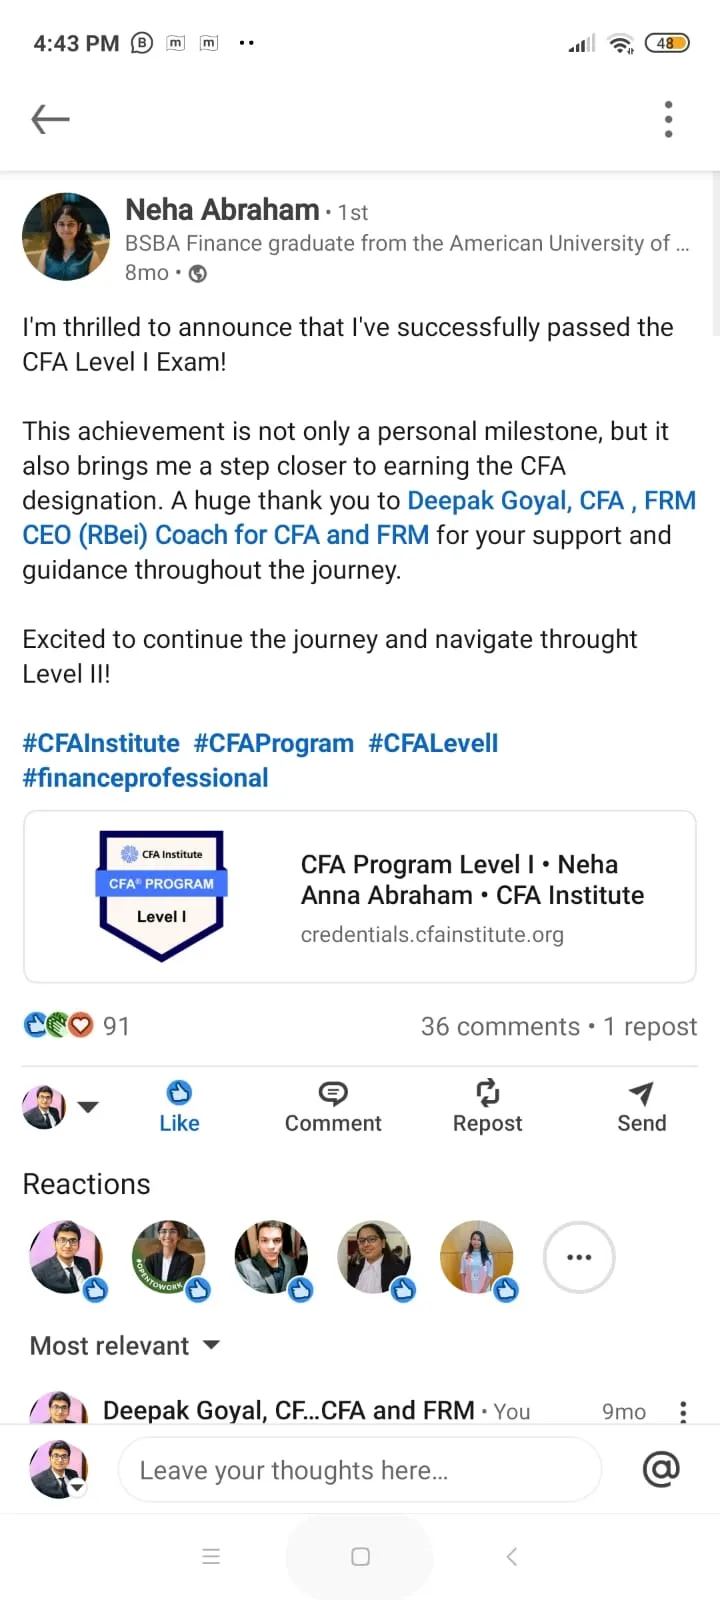
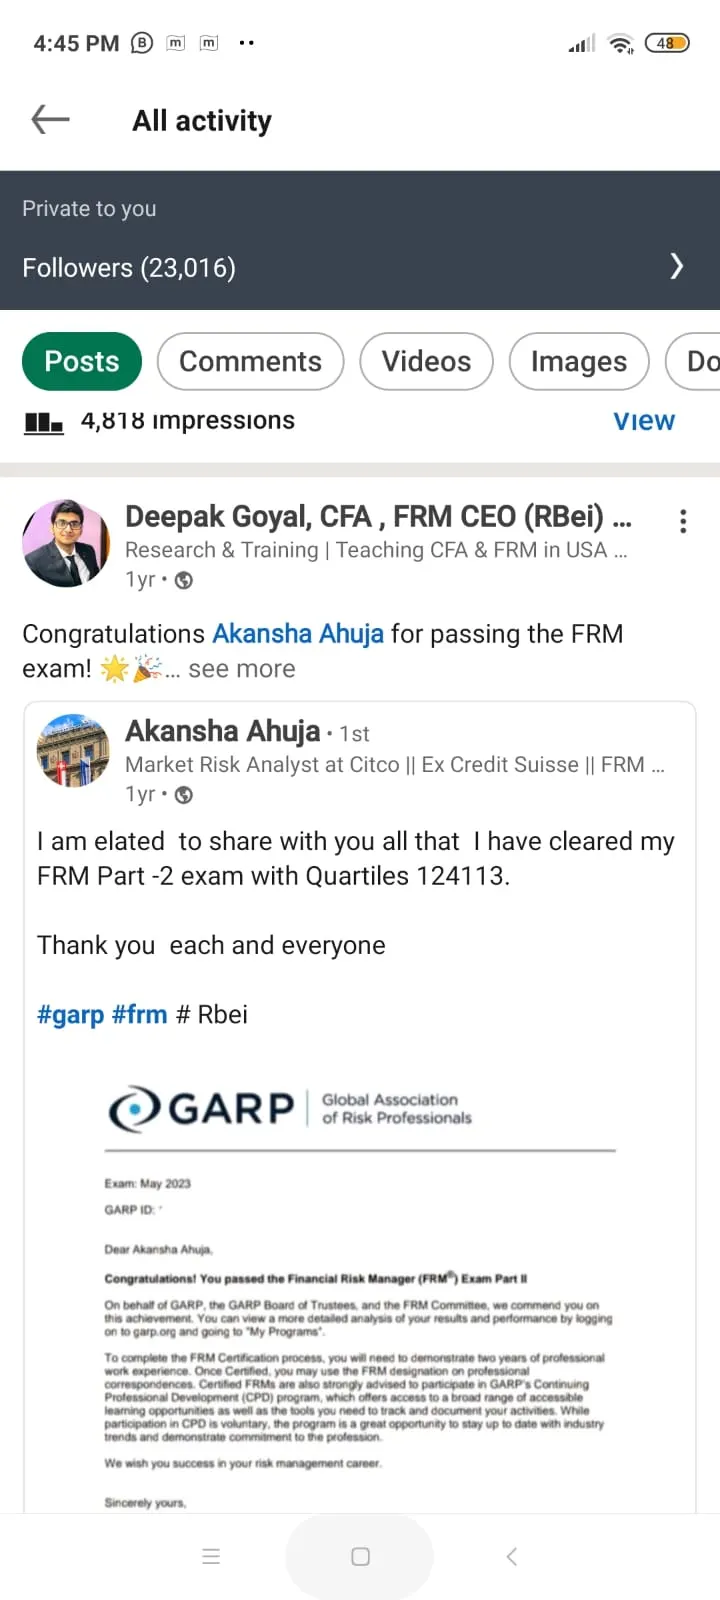
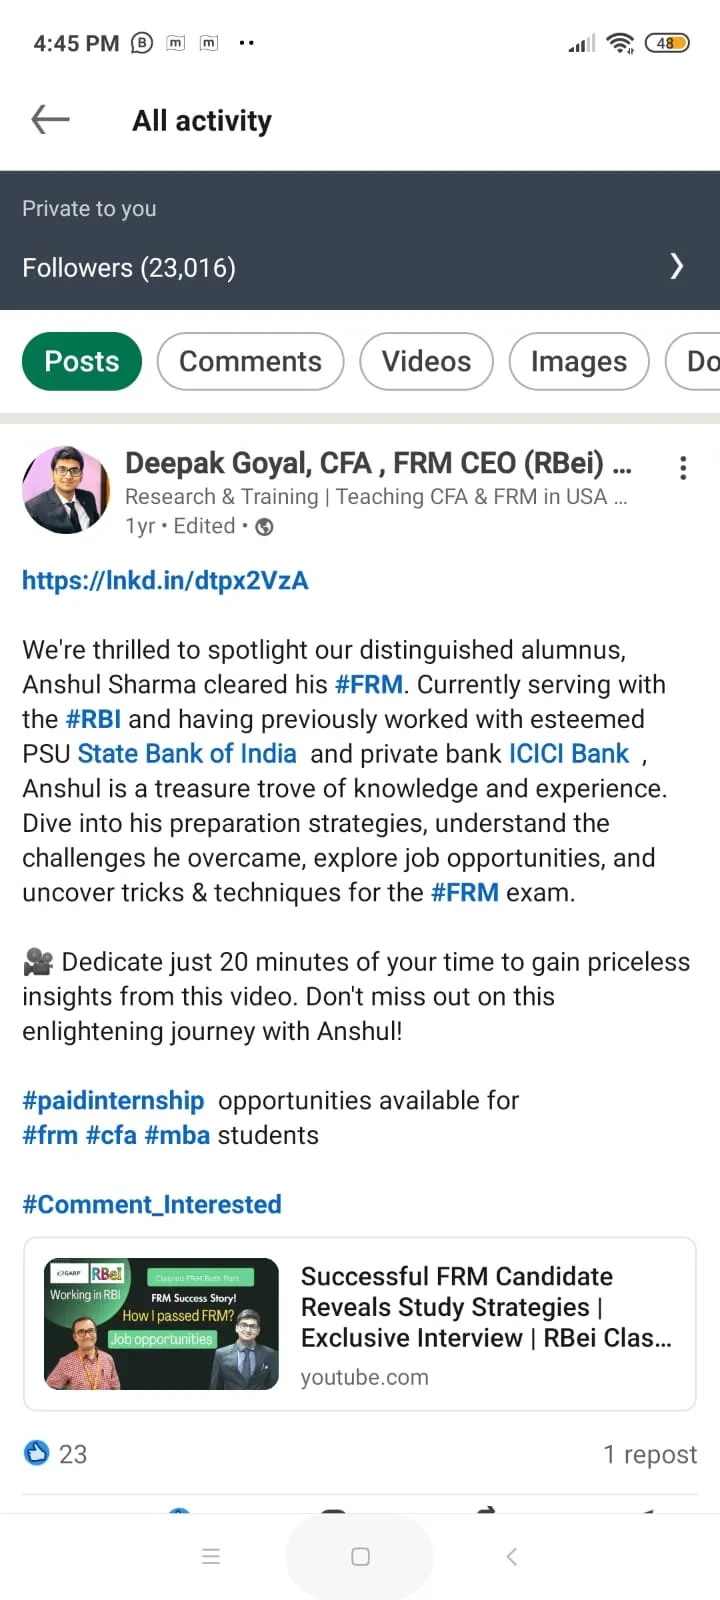
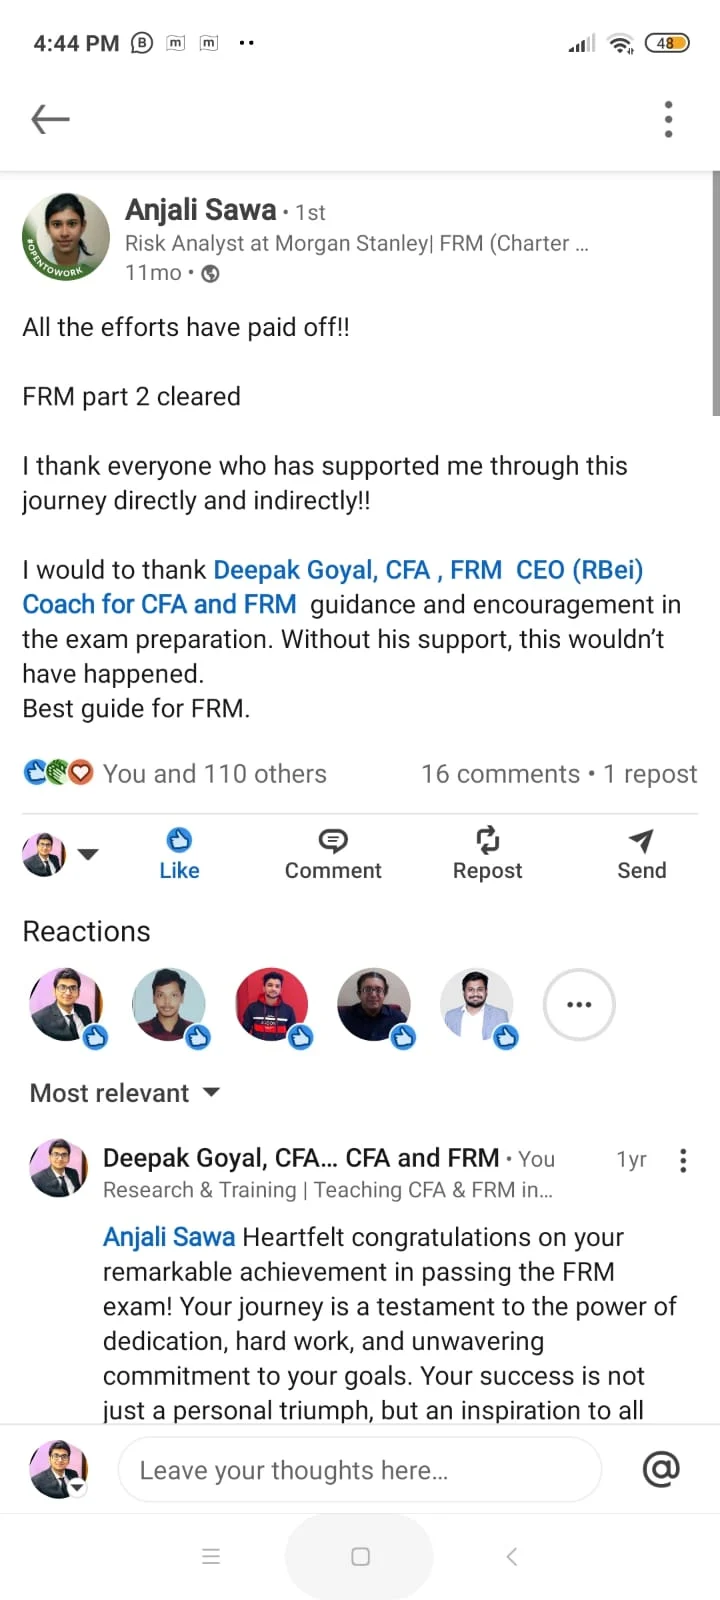
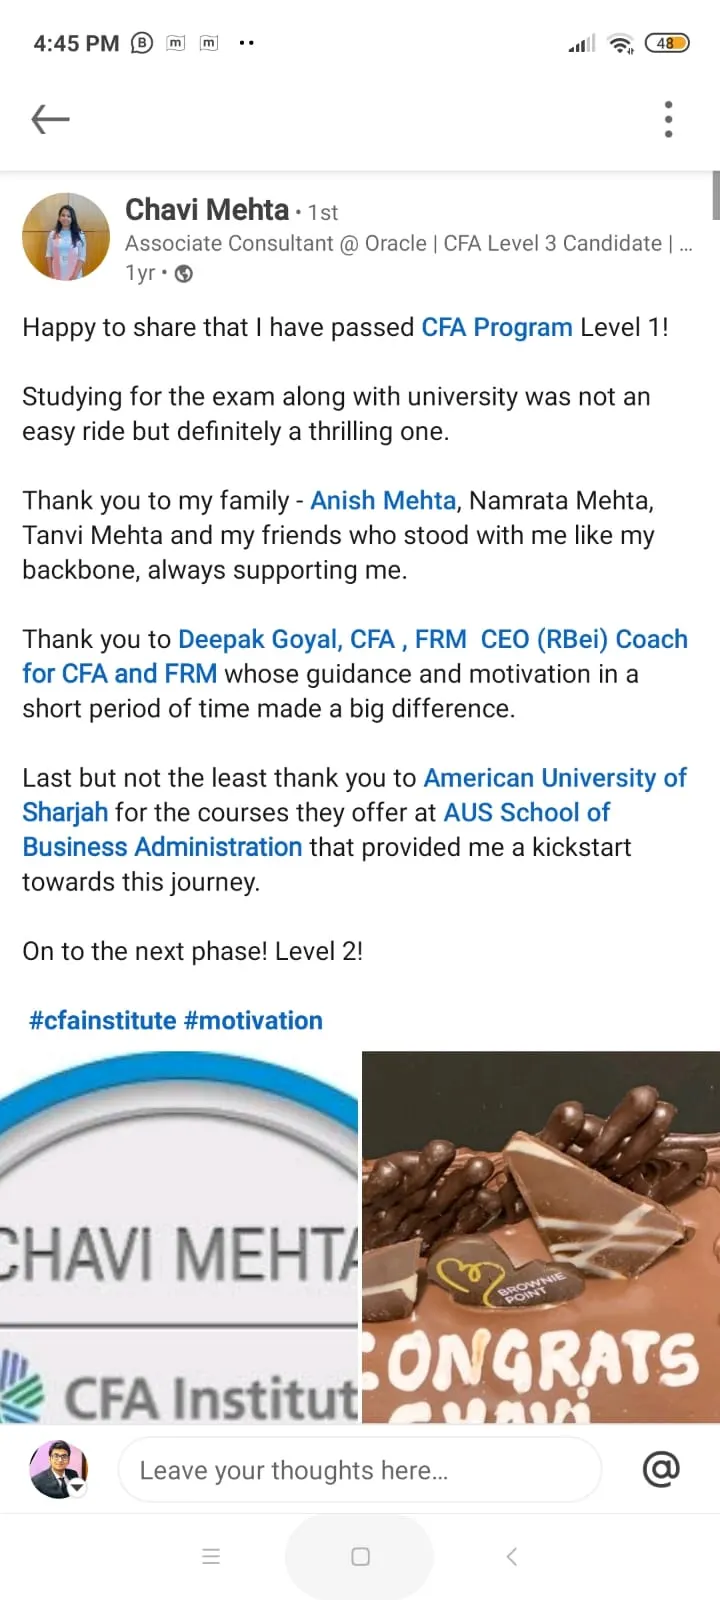
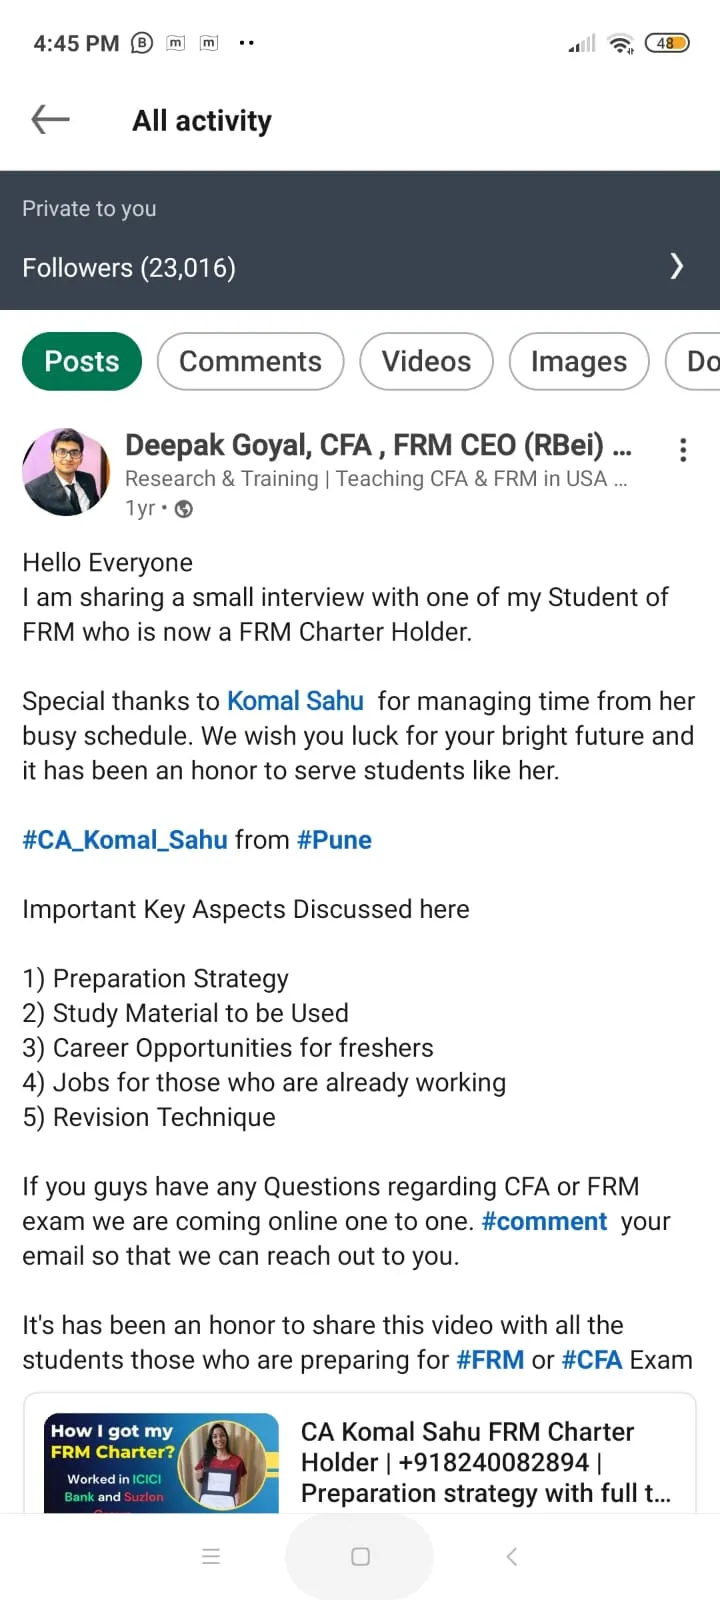
Last updated: June 2026 · Reviewed by: Deepak Goyal, CFA & FRM charterholder, founder of RBei Classes · Public LinkedIn posts shared by RBei Classes students.
RBei Classes, an FRM & CFA coaching institute founded in 2018 by Deepak Goyal (CFA & FRM charterholder), has trained thousands of students since 2018 and holds a 4.9 / 5 aggregate rating across review platforms. The five WhatsApp screenshots below are a small sample of unedited student messages, confirming passes in CFA Level 1 and FRM Part 2 between March 2023 and April 2024.
Last updated: June 2026 · Reviewed by: Deepak Goyal, CFA & FRM charterholder, founder of RBei Classes · Screenshots shared with student consent.