CFA & FRM Coaching by Industry Experts | RBei Classes India
— Reserve your seat →
GARP Official • Updated November 2026

FRM Part 2 Syllabus 2027 — Topics, Weights & Chapters

The complete GARP FRM Part 2 2027 curriculum — all 6 topics, official weights, full chapter breakdown, 2027 changes, study hours & an expert prep plan from Deepak Goyal, CFA & FRM Charterholder at RBei Classes.

Quick Answer

The FRM Part 2 2027 syllabus has 6 topics tested over 80 MCQs in 4 hours: Market Risk (20%), Credit Risk (20%), Operational Risk & Resilience (20%), Liquidity & Treasury Risk (15%), Risk & Investment Management (15%), and Current Issues in Financial Markets (10%). The first three topics carry 60% of the exam.

Based on GARP official curriculum
94% Part 2 pass rate (Aug 2025)
View All 6 Topics ↓

Prefer instant access? Download the Free FRM Part 2 Syllabus 2027 Detailed PDF

Get Free FRM Course Details
Sent instantly on WhatsApp & Email
Please call +91 8583905853

100% free · No spam · Call +91 8583905853

Details received
Stay on this page and complete your ₹99 payment to confirm the 20-minute counselling session with Expert of FRM.
Pay ₹99 →
FRM Part 2 Overview

What Is the FRM Part 2 Syllabus 2027?

RBei Classes, an FRM & CFA coaching institute in Noida, explains it simply: FRM Part 2 is the second and final exam of the GARP Financial Risk Manager programme. Where Part 1 builds the foundational toolkit, Part 2 is about applied risk management — how banks, asset managers and insurers actually measure, manage and report risk. This page details the Part 2 section of the complete FRM syllabus and is part of the FRM coaching programme at RBei Classes.

The 2027 syllabus is organised into six topic areas tested across 80 multiple-choice questions in 4 hours. The three highest-weighted topics — Market Risk, Credit Risk and Operational Risk & Resilience — together carry 60% of the exam, so most study time should go there.

Confirm the 2027 Study Guide (1 Dec 2026) especially for Risk & Investment Management and Current Issues in Financial Markets — those sections typically see the most reading-level churn (alternatives / private markets / hedge funds; AI in risk, scenario generation, digital assets). Older books often leave gaps.

Key Takeaways

  • 6 topics, 80 MCQs, 4 hours, computer-based, no negative marking.
  • Weights: Market 20%, Credit 20%, Operational 20%, Liquidity 15%, Investment 15%, Current Issues 10%.
  • You must pass FRM Part 1 before your Part 2 result counts — see the FRM Part 1 syllabus.
  • Expect the most reading churn in Investment Risk and Current Issues — confirm the Dec 2026 Guide.
  • RBei Classes recorded a 94% Part 2 pass rate in the Aug 2025 window.
FRM Part 2 Syllabus 2027

FRM Part 2 Topics & Weight Breakdown

Official GARP FRM Part 2 syllabus — 6 topics, 80 MCQs, 4 hours. The same topic weights apply for the May, August & November 2027 windows.

FRM Part 2 — 2027 Exam Overview

Focus: applied risk management — market, credit, operational, liquidity, investment & current issues

80
MCQs
4
Hours
6
Topics
~240
Study Hrs
FRM Part 2 Topic (2027)WeightApprox. Questions
Market Risk Measurement & Management20%~16
Credit Risk Measurement & Management20%~16
Operational Risk & Resilience20%~16
Liquidity & Treasury Risk Measurement & Mgmt15%~12
Risk Management & Investment Management15%~12
Current Issues in Financial Markets10%~8
Total100%80 MCQs

Topic Weight Distribution — FRM Part 2 2027

Market Risk Measurement & Mgmt
20%
Credit Risk Measurement & Mgmt
20%
Operational Risk & Resilience
20%
Liquidity & Treasury Risk
15%
Risk & Investment Management
15%
Current Issues in Financial Markets
10%

This section extends the Part 1 VaR toolkit to professional-level market-risk measurement: advanced VaR methodologies, backtesting and VaR mapping, expected shortfall and stressed metrics, term-structure and short-rate models, volatility smiles, exotic options, and the Basel III/IV market-risk capital framework including the Fundamental Review of the Trading Book (FRTB).

  • Estimating Market Risk Measures: Introduction
  • Non-Parametric Approaches to Market Risk
  • Parametric Approaches to Market Risk
  • Backtesting VaR
  • VaR Mapping
  • Expected Shortfall & Stressed Metrics
  • The Science of Term Structure Models
  • The Evolution of Short Rate Models
  • Volatility Smiles & Term Structure
  • Exotic Options & Structured Products
  • Fundamental Review of the Trading Book (FRTB)
  • Stress Testing Banks & Sound Practices
Deepak Sir's Insight: Backtesting, VaR mapping and FRTB are perennial high-yield areas. Be fluent in the difference between parametric, non-parametric and stressed VaR — examiners test the boundaries between methods.
Credit Risk is the most mathematically demanding section of Part 2. It covers default-probability and spread models, portfolio credit risk, structured credit (CDOs and CLOs), counterparty credit risk, credit value adjustment (CVA/DVA), credit derivatives and the regulatory capital framework — the full credit lifecycle from PD/LGD/EAD through to economic capital.

  • Credit Risk & Credit Analysis Fundamentals
  • Country Risk: Determinants & Measurement
  • Spread Risk & Default Intensity Models
  • Portfolio Credit Risk
  • Structured Credit Risk: CDOs & CLOs
  • Counterparty Credit Risk (CCR) Overview
  • Netting, Close-out, Rehypothecation & Margin
  • Credit Value Adjustment (CVA) & DVA
  • Credit Derivatives: CDS & Total Return Swaps
  • Credit Scoring & Retail Credit Risk
  • Expected Loss, Unexpected Loss & Economic Capital
  • Regulatory Capital for Credit Risk (Basel III/IV)
Deepak Sir's Insight: CVA, DVA and counterparty credit risk are the most frequently tested advanced topics. Practise the calculations until they are second nature — conceptual reading alone is not enough here.

Operational Risk covers non-financial risks from processes, people, systems and external events. It focuses on identification, measurement and management under Basel frameworks — governance and risk culture, loss-data collection and severity modelling, scenario analysis, the Standardised Measurement Approach (SMA), model risk and validation, cyber risk, and operational resilience including third-party and business-continuity risk.

  • Operational Risk: Principles & Concepts
  • Basel Operational Risk Framework & Capital
  • The Standardised Measurement Approach (SMA)
  • Operational Risk Governance & Culture
  • Risk & Control Self-Assessment (RCSA)
  • Key Risk Indicators (KRIs) & Metrics
  • Loss Data Collection & Severity Modelling
  • Scenario Analysis for Operational Risk
  • Model Risk & Model Validation
  • Cyber & Information Security Risk
  • Conduct Risk & Culture
  • Operational Resilience, BCP & Third-Party Risk
Deepak Sir's Insight: Conceptual but breadth-heavy. Operational resilience, third-party risk and model validation have grown in prominence — don't treat it as an easy scoring area.

This section covers funding and market liquidity risk and treasury management in banks. Core exam areas are the Liquidity Coverage Ratio (LCR), Net Stable Funding Ratio (NSFR), asset-liability management (ALM), interest-rate risk in the banking book (IRRBB), contingency funding planning, intraday liquidity, fund transfer pricing and liquidity stress testing under Basel III.

  • Liquidity Risk: Definitions & Fundamentals
  • Funding & Liquidity Risk in Banks
  • Liquidity Coverage Ratio (LCR) — Basel III
  • Net Stable Funding Ratio (NSFR) — Basel III
  • Contingency Funding Planning (CFP)
  • Intraday Liquidity Risk
  • Market Liquidity & Liquidity-Adjusted VaR
  • Asset-Liability Management (ALM)
  • Interest Rate Risk in the Banking Book (IRRBB)
  • Funds Transfer Pricing
  • Liquidity Stress Testing
Deepak Sir's Insight: LCR and NSFR mechanics are almost guaranteed. Memorise the components and qualifying-asset haircuts — quick, reliable marks once drilled.

This section applies risk frameworks to investment portfolios — factor models, portfolio construction, risk budgeting, performance attribution and hedge-fund risk. Recent curriculum cycles substantially expanded it with new content on hedge-fund strategies, model validation, alternative investments and private-markets risk, including identifying distress symptoms and red flags. Confirm 2027 Study Guide materials only.

  • Factor Theory & Factor Models
  • Portfolio Construction
  • Portfolio Risk: Analytical Methods
  • VaR & Risk Budgeting in Investment Mgmt
  • Risk Monitoring & Performance Measurement
  • Performance Evaluation (Sharpe, Treynor, Jensen)
  • Hedge Funds: Overview & Risk (Re-check 2027 Guide)
  • Hedge Fund Strategies & Risk (Re-check 2027 Guide)
  • Model Validation Frameworks (Re-check 2027 Guide)
  • Alternative Investments & Private Markets (Re-check 2027 Guide)
  • Risk Mgmt for Pension Funds & Insurers
2027 Note: Re-check private markets, hedge-fund risk and model validation in GARP’s December Study Guide — these areas often see deeper analytical requirements year to year.

Current Issues changes most each year as GARP reflects emerging risks. Recent cycles have been heavy on: artificial intelligence and machine learning in risk management, advanced scenario generation and stress testing, digital assets and crypto risk, systemic risk and interconnectedness, climate/ESG in financial institutions, cyber systemic risk and Basel IV developments. 2024-or-earlier notes will have major gaps.

  • AI & Machine Learning in Risk Management (Re-check 2027 Guide)
  • Scenario Generation & Advanced Stress Testing (Re-check 2027 Guide)
  • Systemic Risk & Interconnectedness
  • Climate Risk & ESG in Financial Institutions
  • Digital Assets, Crypto & Blockchain Risk
  • Cyber Risk: Systemic Implications
  • Regulatory Developments: Basel IV & Beyond
  • Geopolitical & Country Risk Dynamics
Important for 2027: Do not use 2024 or older readings here. Confirm GARP’s official 2027 Current Issues list (Study Guide, 1 Dec 2026) — AI and scenario generation have been major themes in recent cycles.
Prepare FRM Part 2 with Deepak Sir →
2027 Updates

FRM Part 2 2027 Changes — What to Expect

GARP releases the official 2027 Study Guide and Learning Objectives on 1 December 2026. Use this checklist until that PDF is live — Part 2 usually sees more reading churn than Part 1.

Confirm Dec 1

Official 2027 Study Guide

May / August / November 2027 Part 2 sittings follow the 2027 Guide. Diff your notes against GARP’s December Learning Objectives before you finalise revision.

Expected weights

Six topics (working plan)

Market Risk 20%, Credit Risk 20%, Operational Risk 20%, Liquidity & Treasury 15%, Risk & Investment Management 15%, Current Issues 10% — 80 MCQs in 4 hours, unless GARP revises the map.

Usually stable

Market / Credit / OpRisk / Liquidity

These four pillars are typically stable on core frameworks (VaR / FRTB, CVA, Basel SMA, LCR / NSFR). Still verify chapter lists in the December Guide.

Re-check

Risk & Investment Management

Recent cycles deepened private markets, hedge-fund risk and model validation. Confirm the 2027 readings on 1 Dec 2026 — older notes often miss additions.

Highest churn

Current Issues in Financial Markets

Usually the most updated Part 2 section (AI / ML in risk, scenario generation, digital assets, ESG, geopolitics). Do not rely on 2024 or older materials.

Action

What to do now

Keep studying the six-topic weight map above, then update Investment Risk and Current Issues first when the December Guide drops.

Always confirm the latest readings at garp.org/frm.

Exam Structure

FRM Part 2 2027 — Exam Pattern & Dates

Format, rules and the 2027 exam windows for FRM Part 2.

📋 Exam Format

ParameterFRM Part 2
Number of questions80 MCQs
Duration4 hours
FormatComputer-based (CBT)
Question typeMultiple-choice only
Formula sheetNot provided
CalculatorGARP-approved models only
Negative markingNo
PrerequisiteMust pass Part 1 first
Global pass rate~55–60%

📅 FRM Part 2 2027 Exam Dates

WindowExam Dates (Part II)Early RegistrationStandard Deadline
May 2027 ▶May 15–17, 2027Dec 1, 2026 – Jan 31, 2027Feb 1 – Mar 31, 2027
August 2027 ▶August 13–14, 2027 (PM)Mar 1 – Apr 30, 2027May 1 – Jun 30, 2027
November 2027 ▶November 20–22, 2027May 1 – Jul 31, 2027Aug 1 – Oct 29, 2027

Deadlines are 11:59 pm Eastern Time. August Part II is PM sessions (Part I AM on the same dates). Confirm at garp.org/frm/exam-logistics. Part 2 is only for candidates who have passed Part 1.

Study Planning

FRM Part 2 2027 — Study Hours by Topic

Recommended hours per topic, based on GARP candidate surveys and RBei student data (~240 hours total).

45–55
Hours
Market Risk Measurement
Advanced VaR, FRTB, backtesting — builds on Part 1
45–55
Hours
Credit Risk Measurement
Hardest section — CVA, structured credit, portfolio models
35–45
Hours
Operational Risk & Resilience
Governance, Basel frameworks, model risk, resilience
30–35
Hours
Liquidity & Treasury Risk
LCR, NSFR, ALM, IRRBB, intraday liquidity
30–35
Hours
Risk & Investment Mgmt
Re-check 2027 Guide — model validation, hedge funds, private markets
20–25
Hours
Current Issues 2027
Confirm Dec Guide — AI, scenario generation, ESG, crypto
~240
Total Hours
FRM Part 2
Recommended minimum (candidate surveys)
Salary & ROI

Why FRM Part 2 Is Worth It — Salary & Career ROI

Clearing FRM Part 2 completes the GARP designation (with 2 years' experience) and unlocks senior risk roles across banking and finance.

Role / Experience (India)Typical Salary (LPA)
Entry-level risk analyst (FRM Part 1 + fresher)₹6–9 LPA
FRM-certified risk associate (2–4 yrs)₹9–14 LPA
Risk / market-risk manager (5–8 yrs)₹15–25 LPA
Senior / VP risk (8+ yrs)₹30 LPA+

Salary ranges are indicative of the Indian market and vary by employer, city and experience. RBei Classes alumni work at firms including JPMorgan, Goldman Sachs, HSBC, KPMG and HDFC Bank, with several placed across Dubai, the US, Canada and Singapore.

Expert Strategy

FRM Part 2 2027 — Phase-by-Phase Plan

RBei Classes, an FRM & CFA coaching institute, recorded FRM Part 2 pass rates of 90% (May 2025), 94% (Aug 2025) and 87% (Nov 2025) — calculated for students who actually sat the exam in each window. Here's the framework behind it.

Phase 1 — Core Risk (Weeks 1–8)

  • Start with Market, then Credit and Operational Risk — the 60% weight block
  • Do chapter-level practice questions as you finish each reading, not at the end
  • Drill CVA/DVA, FRTB and backtesting calculations until they're automatic

Phase 2 — Remaining Topics (Weeks 9–14)

  • Lock in Liquidity & Treasury Risk — LCR/NSFR are quick, reliable marks
  • Cover Risk & Investment Management using 2027 Study Guide materials for the new content
  • Read Current Issues last, from 2027 readings only — AI, scenario generation, ESG

Phase 3 — Mocks & Revision (Weeks 15–18)

  • Take at least 3 full-length CBT mocks under timed conditions
  • Analyse every wrong answer — understand why, not just the right option
  • Prioritise the 60% block for final revision: Market + Credit + Operational Risk
Deepak Goyal, CFA and FRM Charterholder, founder of RBei Classes
Deepak Goyal
CFA Charterholder & FRM Charterholder
CFA Institute GARP FRM

Deepak Goyal is a CFA & FRM Charterholder with ~10 years in investment banking across India, the US and Dubai and 8 years of teaching. He founded RBei Classes in 2018 and has personally mentored 17,000+ CFA and FRM students.

8 yrs
Teaching
17K+
Mentored
94%
P2 Aug'25
View LinkedIn Profile ↗ Verify FRM Credential at GARP ↗
FAQ

FRM Part 2 Syllabus 2027 — Frequently Asked Questions

Everything candidates ask about the FRM Part 2 2027 syllabus — answered by Deepak Sir.

The FRM Part 2 2027 syllabus, published by GARP, covers six topic areas across 80 MCQs in 4 hours: Market Risk (20%), Credit Risk (20%), Operational Risk & Resilience (20%), Liquidity & Treasury Risk (15%), Risk & Investment Management (15%) and Current Issues in Financial Markets (10%). Part 2 focuses on applied risk management.
Market Risk, Credit Risk and Operational Risk are each 20% (~16 questions each); Liquidity & Treasury Risk and Risk & Investment Management are each 15% (~12 questions each); Current Issues is 10% (~8 questions). The top three topics together make up 60% of the exam.
FRM Part 2 has 80 multiple-choice questions in 4 hours. It is a computer-based test with no negative marking. Formula sheets are not provided, but a GARP-approved calculator is allowed.
GARP publishes the official FRM 2027 Study Guide and Learning Objectives on 1 December 2026. Until that release, plan around the same six Part 2 topic weights (Market 20%, Credit 20%, Operational 20%, Liquidity 15%, Investment 15%, Current Issues 10%). Current Issues and Risk & Investment Management typically see the most reading-level churn — confirm the December Guide before May, August or November 2027.
Credit Risk Measurement & Management is widely considered the hardest. It's the most mathematically demanding section — CVA/DVA, counterparty credit risk, structured products (CDOs, CLOs) and portfolio credit models — and rewards heavy numerical practice.
GARP candidate surveys suggest around 240 hours. With RBei coaching, most students prepare over 4–5 months at roughly 90 minutes on weekdays plus weekend sessions, supported by mock exams and topic-wise practice questions.
The global FRM Part 2 pass rate is historically around 55–60%. RBei Classes recorded Part 2 pass rates of 90% (May 2025), 94% (Aug 2025) and 87% (Nov 2025), calculated for students who actually sat the exam in each window.
Yes. Your Part 2 result is only recognised once Part 1 is passed. If you sit both on the same day, GARP will not mark Part 2 unless you pass Part 1. Most candidates take the two parts in separate windows.
Yes. GARP keeps the FRM Part 2 2027 syllabus and weights identical across all 2027 windows. The curriculum does not change mid-year, so the same readings and learning objectives apply for August and November 2027.
GARP publishes the official FRM Learning Objectives and Study Guide as a free PDF at garp.org/frm/study-materials. RBei Classes also provides a free, detailed FRM Part 2 2027 syllabus PDF for instant download, and shares a condensed version with students via WhatsApp and email.

Ready to clear FRM Part 2 in 2027?

Live online coaching by Deepak Goyal, CFA & FRM — recorded lectures, full mocks & topic-wise practice. 94% Part 2 pass rate (Aug 2025 window).

Enroll in FRM Coaching →
Verified on LinkedIn

RBei Classes Student Success on LinkedIn

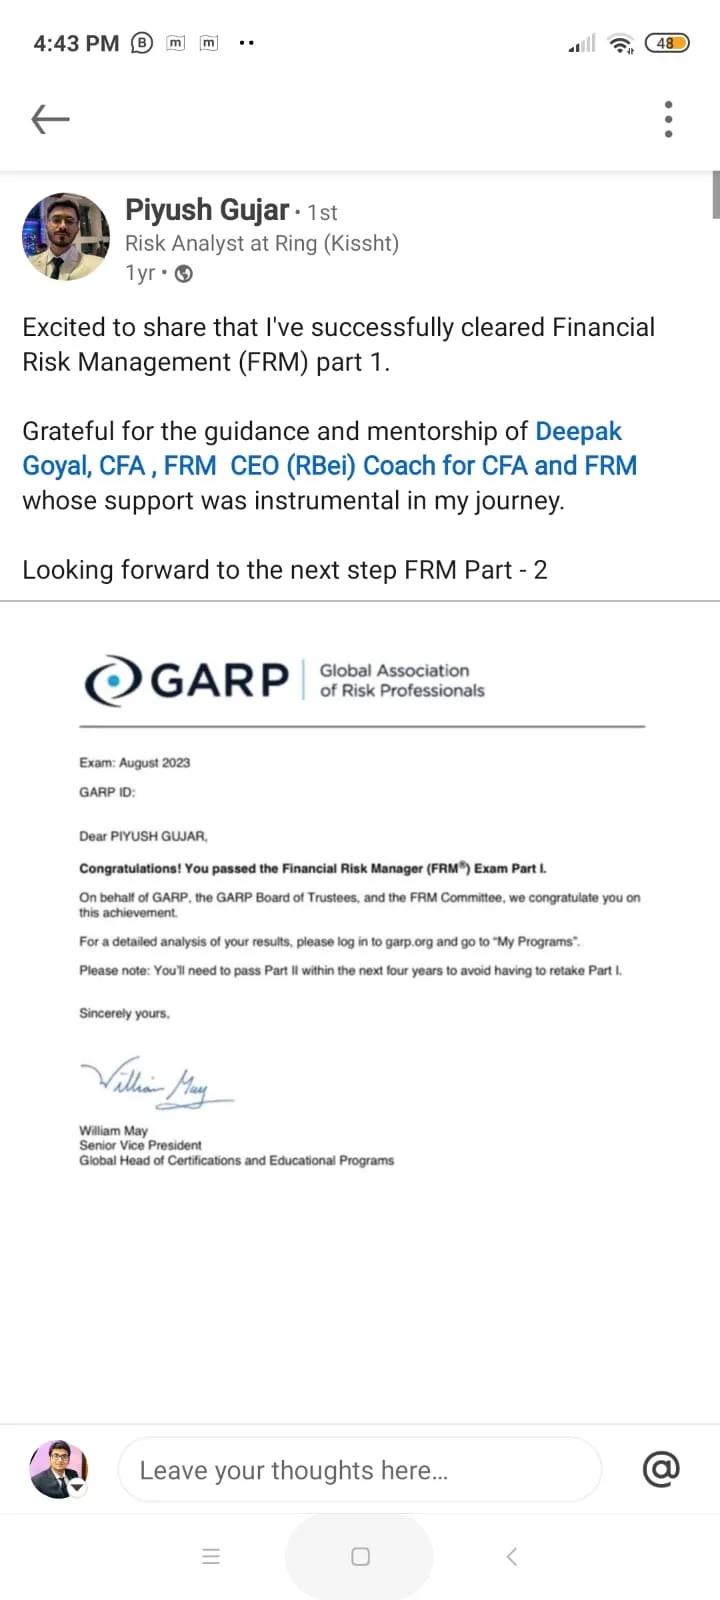
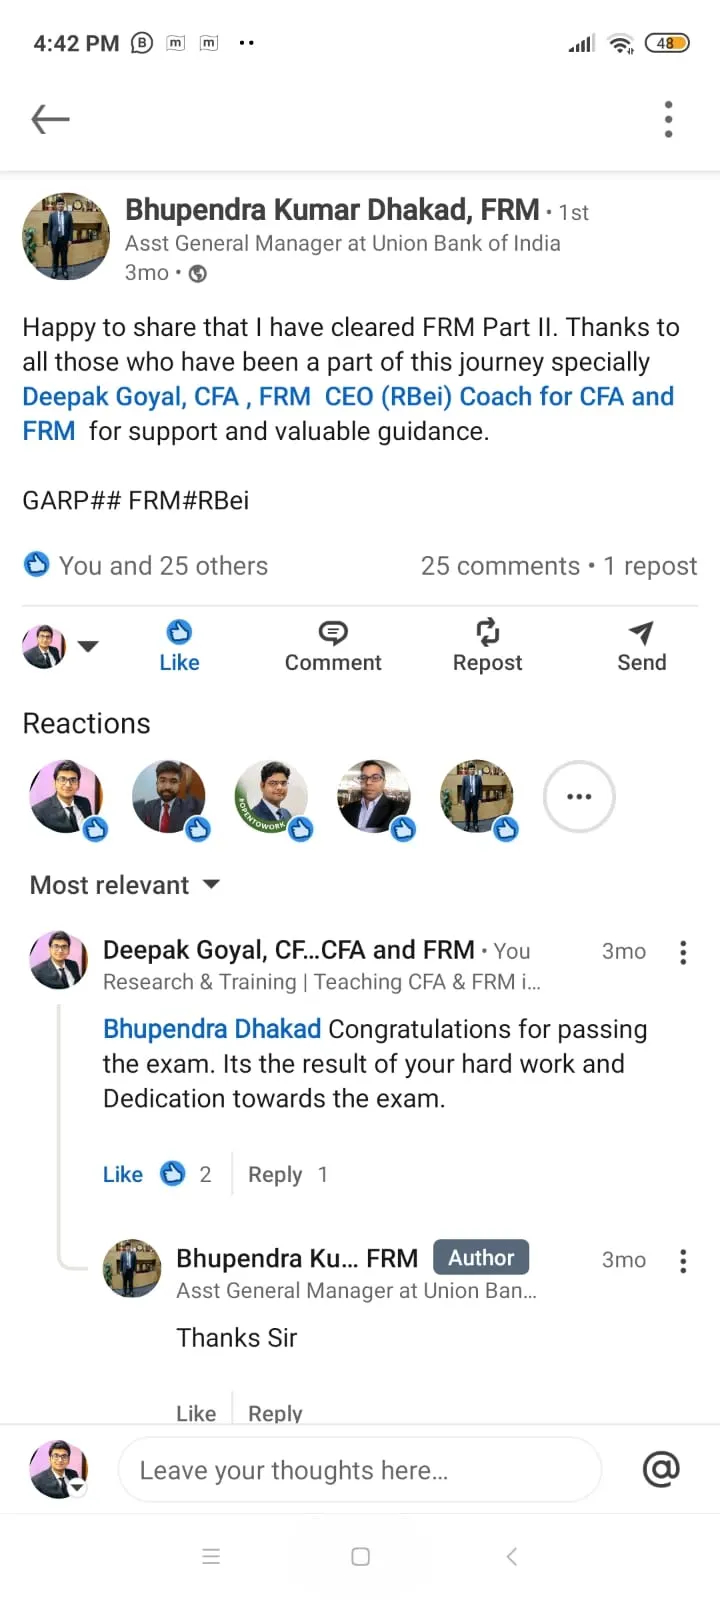
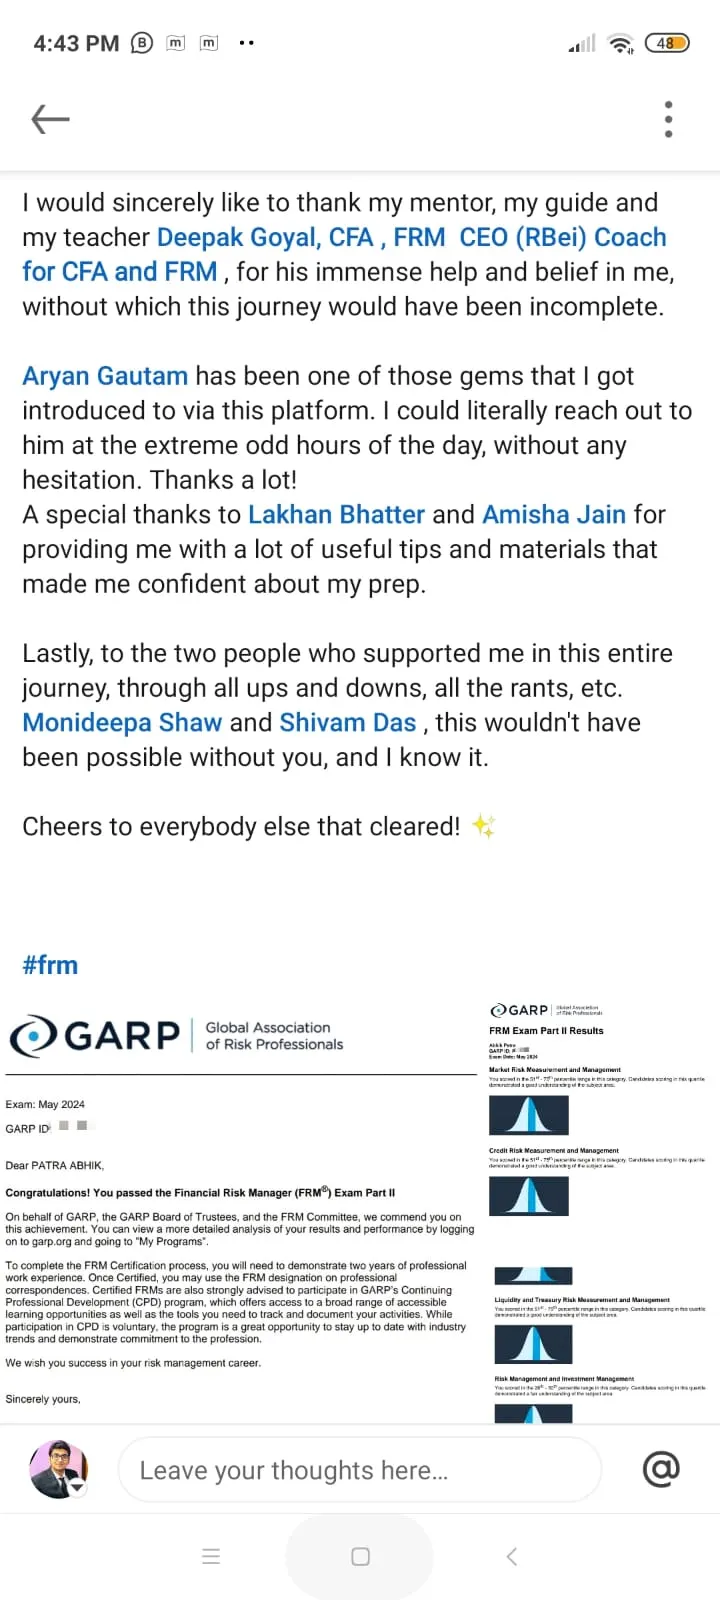
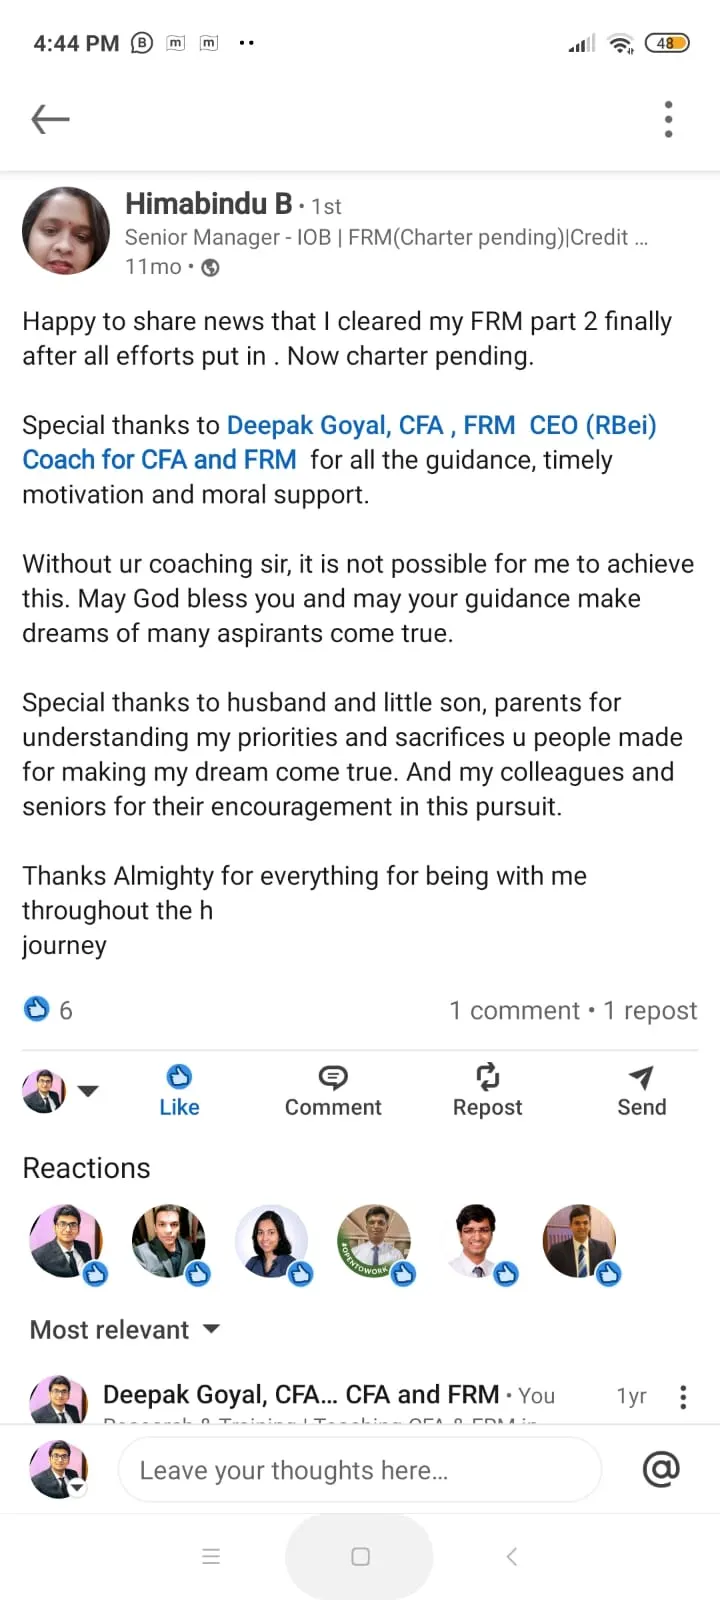
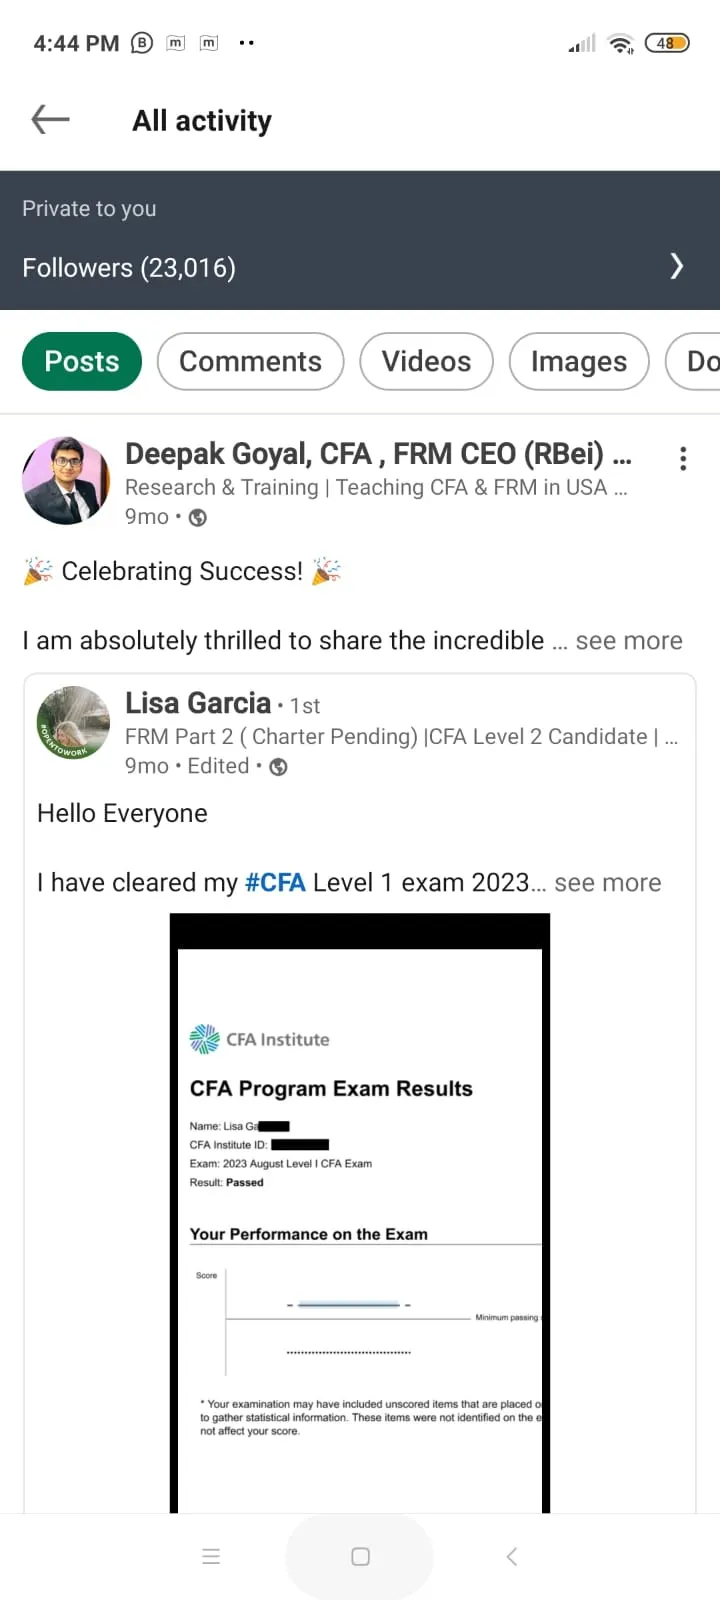
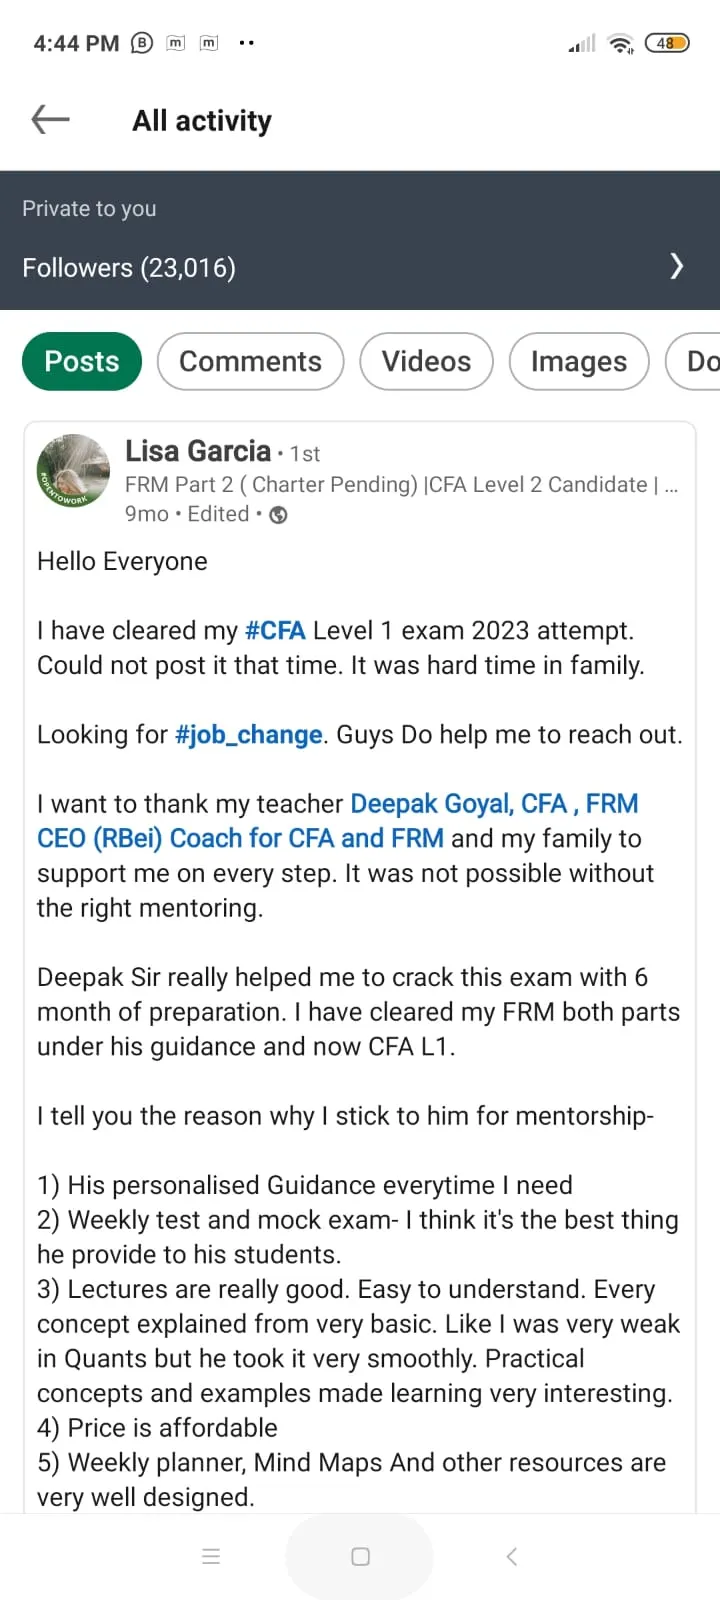
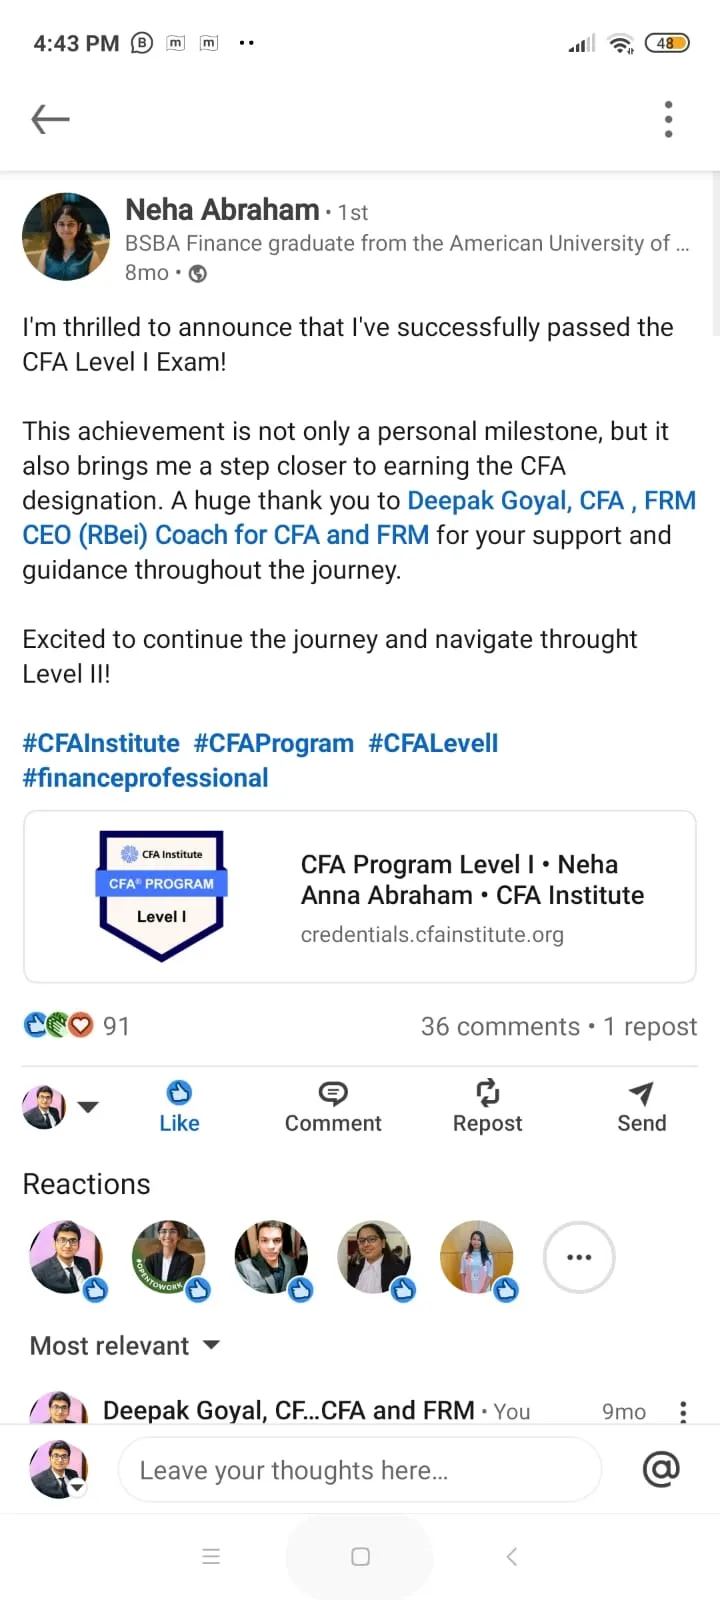
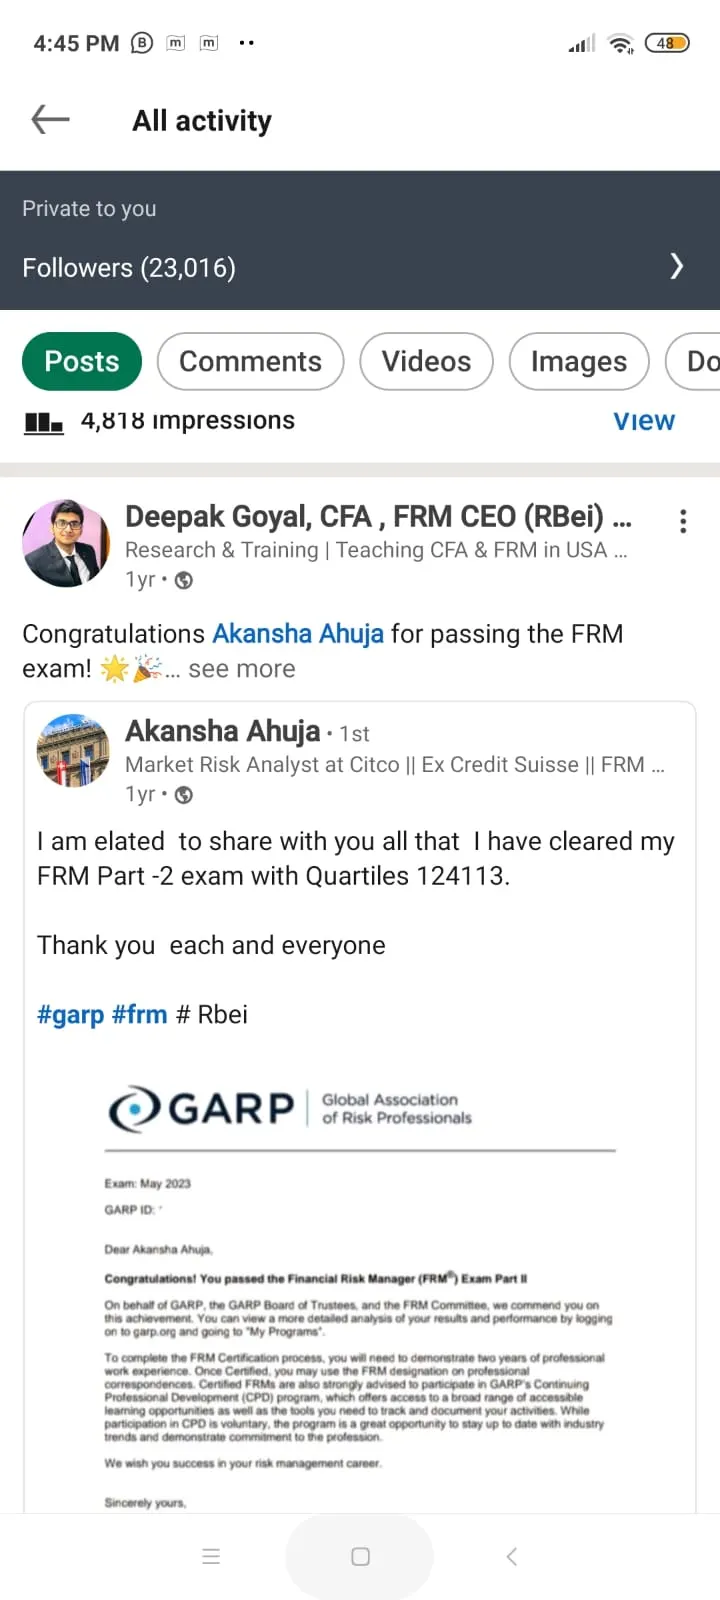
RBei Classes, an FRM & CFA coaching institute founded in 2018 by Deepak Goyal (CFA & FRM charterholder), has trained thousands of students who share their results publicly on LinkedIn. The 13 posts below are a sample of RBei Classes students announcing verified CFA and FRM passes — public, name-attributed proof of outcomes.

Key Takeaways

  • RBei Classes students publicly share verified CFA and FRM results on LinkedIn, with name and profile attached.
  • The 13 posts shown are a sample of the thousands of students trained by RBei Classes since 2018.
  • Outcomes span CFA Level 1, CFA Level 2 prep, and FRM Part 1 & 2.
  • Coaching is led by Deepak Goyal, CFA & FRM charterholder, founder of RBei Classes.

Last updated: June 2026 · Reviewed by: Deepak Goyal, CFA & FRM charterholder, founder of RBei Classes · Public LinkedIn posts shared by RBei Classes students.

Verified Student Feedback

RBei Classes Reviews — Verified FRM & CFA Student Results

RBei Classes, an FRM & CFA coaching institute founded in 2018 by Deepak Goyal (CFA & FRM charterholder), has trained thousands of students since 2018 and holds a 4.9 / 5 aggregate rating across review platforms. The five WhatsApp screenshots below are a small sample of unedited student messages, confirming passes in CFA Level 1 and FRM Part 2 between March 2023 and April 2024.

Key Takeaways

  • RBei Classes has trained thousands of students since 2018 and holds a 4.9/5 aggregate rating across review platforms.
  • Verified students cleared CFA Level 1, CFA Level 2 prep, and FRM Part 1 & 2 between 2018 and 2026.
  • All reviews are unedited WhatsApp messages shared with student consent.
  • Coaching is led by Deepak Goyal, CFA & FRM charterholder, founder of RBei Classes.

Last updated: June 2026 · Reviewed by: Deepak Goyal, CFA & FRM charterholder, founder of RBei Classes · Screenshots shared with student consent.

Alumni Success

RBei Classes Alumni Success Stories

Verified RBei Classes alumni working in risk and banking roles across India.

★★★★★
Sunil Tandon, Chief Risk Officer at Punjab & Sind Bank and RBei Classes FRM alumnus
Sunil Tandon

Chief Risk Officer, Punjab & Sind Bank

FRM cleared with RBei Classes

“I cleared the FRM exam with the help of RBei Classes. The concepts were explained so clearly that even difficult topics started making sense. The classes gave me the confidence I needed for the exam.”

Risk Management Retail Banking Operational Risk Market Risk
View LinkedIn ↗
★★★★★
Sanya Reddy, Manager at Bank of Baroda and RBei Classes FRM and CFA alumna
Sanya Reddy

Manager, Bank of Baroda

FRM Part 2 & CFA Level 2 passed

“What helped me the most was the doubt-solving support at RBei Classes. Whenever I got stuck, my questions were answered quickly and clearly. That guidance played a big role in helping me clear the FRM exam.”

Risk Management Investment Banking Credit Risk
View LinkedIn ↗
★★★★★
Payal Sharma, risk management professional and RBei Classes FRM alumna
Payal Sharma

Risk Management Professional · Ex-SBI & HSBC

FRM Part 1 cleared · CAIIB / JAIIB

“The study material provided by RBei Classes was concise and exam-focused. Instead of spending time on unnecessary content, I could focus on what really mattered for the FRM exam and eventually pass.”

Financial Risk Retail Banking Credit Risk Market Risk Liquidity Risk
View LinkedIn ↗

Ready to Clear Your CFA or FRM Exam?

Join 17,000+ students coached by Deepak Goyal, CFA & FRM Charterholder

17,000+ Students Trained
93% Pass Rate
350+ Batches Done
4.9/5 Average Rating
95% Students Placed
25+ Countries